25Sep

Relieving Letter, Experience Letter and Settlement Documents: Understanding the Difference

By Afla KC , Digital Marketing Executive

Introduction

When an employee leaves an organisation, HR’s responsibility does not end with accepting the resignation.

The exit process involves several important steps, including notice-period management, handover, access removal, payroll closure, statutory updates, and the preparation of employment-related documents.

Among the most commonly discussed documents are the Relieving Letter, Experience Letter, and Full and Final Settlement documents.

Although these documents are often mentioned together, they serve different purposes.

A relieving letter confirms that an employee has been formally released from their responsibilities. An experience letter records the employee’s work experience with the organisation. Settlement documents, on the other hand, deal primarily with the financial and administrative closure of the employment relationship.

Understanding the difference is important for both HR teams and employees. It helps organisations maintain a professional exit process and ensures that employees receive the documentation they may need for future employment, background verification, financial records, or other purposes.

In this guide, we will explain what each document means, when it is issued, what information it generally contains, and how HR teams can manage the employee exit process more effectively.


What Is a Relieving Letter?

A Relieving Letter i

s a document issued by an employer confirming that an employee has been formally relieved from their duties.

It generally indicates that the employee has completed the required exit formalities and that their employment with the organisation has ended.

A relieving letter may contai

n:

  • Employee name

  • Designation

  • Employee ID

  • Date of joining

  • Last working day

  • Confirmation of being relieved

  • Reference to resignation, where appropriate

  • Company details

  • Authorised signatory

The document primarily focuses on the employee’s release from employment.


Why Is a Relieving Letter Important?

A relieving letter can be useful when an employee joins another organisation.

A new employer may request it as part of their employment verification process.

It can help confirm t

hat:

  • The employee worked for the previous organisation

  • The employee has formally left

  • The previous employment relationship has ended

However, the exact docu
mentation requirements can vary between employers.

A relieving letter should therefore not be confused with a document that describes the employee’s complete work experience.


What Is an Experience Letter?

An Experience Letter is a document that confirms an employee’s work experience with an organisation.

It generally focuses on the employee’s employment history and may mention:

  • Employee name

  • Designation

  • Department

  • Date of joining

  • Last working date

  • Duration of employment

  • Nature of role or responsibilities

  • Overall employment confirmation

An experience letter is particularly useful when an employee applies for another job and needs to demonstrate previous professional experience.


Relieving Letter vs Experience Letter

The easiest way to understand the difference is:

Relieving Letter = Confirms the employee has been formally released.

Experience Letter = Confirms the employee’s work experience with the organisation.

Although some organisations combine both into a single document, they are conceptually different.

For example, an experience letter may explain that an employee worked as a Marketing Executive from a particular date to another date.

A relieving letter may state that the employee was formally relieved from their duties on their last working day after completing the required exit process.


What Are Settlement Documents?

Settlement documents relate to the financial and administrative closure of an employee’s employment.

The most commonly used term is Full and Final Settlement (FnF).

When an employee leaves, the organisation needs to calculate the amounts payable to and recoverable from the employee.

Depending on the employee’s circumstances and company policies, the settlement may include:

  • Salary payable

  • Leave encashment, where applicable

  • Incentives

  • Bonus, where applicable

  • Reimbursements

  • Deductions

  • Notice-period recovery, where applicable

  • Advances

  • Other recoveries

  • Statutory deductions

The exact components depend on the employment contract, company policies, applicable laws, and the employee’s circumstances.


What Is Full and Final Settlement?

Full and Final Settlement is the process of closing the employee’s financial account with the organisation after the employment relationship ends.

The payroll team generally reviews:

Earnings

  • Salary for the final period

  • Eligible incentives

  • Leave encashment

  • Reimbursements

  • Other applicable payments

Deductions

  • Notice-period recovery, where applicable

  • Salary advances

  • Loans

  • Asset recovery

  • Statutory deductions

  • Other authorised deductions

The final amount is then calculated and processed according to the applicable company procedure and legal requirements.


Why Is Full and Final Settlement Important?

A properly managed settlement helps both the employer and employee close the employment relationship clearly.

For employees, it provides clarity about:

  • Amount payable

  • Deductions

  • Leave balance

  • Pending reimbursements

  • Other financial components

For employers, it creates a documented record of the financial closure of employment.

A clear settlement process can also reduce misunderstandings and disputes after an employee leaves.


Are Relieving and Experience Letters the Same as Full and Final Settlement?

No.

These documents serve different purposes.

DocumentPrimary PurposeRelieving LetterConfirms formal release from employmentExperience LetterConfirms employment experience and tenureFull & Final SettlementCloses financial dues and recoveriesSalary/Tax DocumentsProvide payroll or tax-related information

They may be issued around the same time, but they are not interchangeable.


What Information Should an HR Exit File Contain?

A well-maintained employee exit file may include:

  • Resignation letter

  • Resignation acceptance

  • Notice-period details

  • Handover confirmation

  • Last working day confirmation

  • Exit interview records

  • Asset-return confirmation

  • Access clearance

  • Relieving letter

  • Experience letter

  • Full and Final Settlement statement

  • Salary records

  • Applicable statutory records

  • Other relevant exit documentation

The exact documents will depend on the organisation’s policies and applicable legal requirements.


The Employee Exit Process

A structured exit process can make documentation easier.

Step 1: Receive Resignation

HR formally records the employee’s resignation.

Step 2: Confirm Notice Period

The applicable notice period is reviewed based on the employment contract and company policy.

Step 3: Plan Handover

The employee completes the required knowledge and responsibility transfer.

Step 4: Complete Clearance

HR and relevant departments confirm the return of company assets and completion of required formalities.

Step 5: Confirm Last Working Day

The organisation records the employee’s official final working date.

Step 6: Process Payroll

The payroll team calculates salary and other payable or recoverable amounts.

Step 7: Complete Full and Final Settlement

The final settlement is prepared and processed.

Step 8: Issue Employment Documents

The organisation issues applicable relieving, experience, and other documents according to its process.


What Should a Relieving Letter Include?

A professional relieving letter should generally be concise.

It may include:

Employee name

Designation

Employee ID

Date of joining

Last working date

Confirmation of relief

Authorised signatory

The document does not normally need to contain a detailed description of the employee’s responsibilities.

That information is generally more appropriate for an experience or employment certificate.


What Should an Experience Letter Include?

An experience letter may provide slightly more detail.

It can mention:

  • Employee’s full name

  • Position held

  • Department

  • Employment period

  • Key responsibilities, where appropriate

  • General statement regarding employment

  • Date of issue

  • Company details

  • Authorised signatory

Some organisations issue a simple experience certificate, while others provide a more detailed employment certificate.


What Should a Full and Final Statement Include?

A settlement statement should clearly show the relevant financial components.

It may include:

Earnings

  • Salary

  • Leave encashment

  • Incentives

  • Bonus

  • Reimbursements

Deductions

  • Statutory deductions

  • Notice-period recovery

  • Advances

  • Loans

  • Other authorised recoveries

Final Amount

The statement should clearly show the net amount payable or recoverable after applicable calculations.

Employees should be able to understand how the final amount was calculated.


When Should These Documents Be Issued?

There is no single universal timeline that applies identically to every organisation and situation.

The timing may depend on:

  • Company policy

  • Employment contract

  • Applicable labour laws

  • Completion of clearance

  • Payroll processing

  • Full-and-final settlement

  • Statutory requirements

HR teams should establish a clear internal process and communicate expected timelines to employees.

Avoid leaving employees uncertain about when they will receive their exit documentation.


Common HR Mistakes During Employee Exit

1. Treating All Documents as the Same

Relieving letters, experience letters, and settlement statements serve different purposes.

2. Incomplete Exit Records

Missing resignation acceptance, clearance, or settlement documentation can create future complications.

3. Delayed Communication

Employees should understand the exit process and expected timelines.

4. Incorrect Final Payroll

Salary, leave, incentives, recoveries, and deductions should be reviewed carefully.

5. Poor Documentation

Important exit records should be stored securely and systematically.

6. Inconsistent Processes

Different employees should not receive completely different exit treatment without a valid reason.


Common Employee Questions

Can an Experience Letter Replace a Relieving Letter?

Not necessarily.

An experience letter confirms employment experience, while a relieving letter generally confirms formal release from employment.

Some organisations may combine the two into a single document, but employees should check what documentation their next employer requires.

Is a Full and Final Settlement the Same as a Relieving Letter?

No.

Full and Final Settlement deals with financial closure. A relieving letter deals with the employee’s formal release from employment.

Can an Employee Request These Documents?

Employees can request relevant employment documents from their employer, subject to the organisation’s processes and applicable requirements.

Does Every Company Use Separate Documents?

No.

Some organisations issue separate relieving and experience letters, while others provide a combined employment or relieving-and-experience letter.


How HRMS Can Simplify Employee Exit Management

Employee exits involve multiple departments and several documents.

An HRMS can help organisations manage:

  • Resignation records

  • Notice periods

  • Exit approvals

  • Clearance

  • Asset tracking

  • Leave balances

  • Payroll calculations

  • Full-and-final settlement

  • Document generation

  • Employee records

A structured digital workflow reduces manual follow-ups and makes it easier for HR teams to track the status of each employee’s exit.


Employee Exit Checklist for HR Teams

Before closing an employee’s file, HR teams can check:

✓ Resignation received

✓ Resignation accepted

✓ Notice period confirmed

✓ Handover completed

✓ Company assets returned

✓ Access removed

✓ Leave balance verified

✓ Final salary calculated

✓ Statutory deductions reviewed

✓ Full and Final Settlement completed

✓ Relieving Letter prepared

✓ Experience Letter prepared

✓ Other applicable documents issued

✓ Exit records securely maintained

This checklist can help create a consistent employee exit process.


Why a Professional Exit Process Matters

An employee’s final experience with a company can influence how they remember the organisation.

A well-managed exit demonstrates professionalism.

Even when an employee is leaving for another opportunity, the organisation can maintain a positive relationship through:

  • Clear communication

  • Timely documentation

  • Accurate settlement

  • Respectful exit discussions

  • Proper handover

  • Professional closure

Former employees can also become future clients, business partners, referrals, or even potential rehires.

Therefore, employee offboarding should be treated as an important part of the overall employee experience.


Conclusion

Relieving Letters, Experience Letters, and Full and Final Settlement documents are all important parts of employee offboarding, but they serve different purposes.

A Relieving Letter primarily confirms that an employee has been formally released from their employment.

An Experience Letter records the employee’s professional experience and period of employment.

Full and Final Settlement documents deal with the financial closure of the employment relationship, including applicable earnings, deductions, recoveries, and other settlement components.

For HR teams, understanding these differences helps create a more structured and transparent exit process. It also reduces confusion for employees who may need these documents when joining a new organisation.

The best approach is to establish a standard exit checklist, clearly assign responsibilities, maintain accurate payroll records, and communicate timelines to employees. Using HRMS and payroll systems can further simplify document management and reduce manual errors.

Employee exits are a normal part of business operations. What matters is how professionally the organisation manages them.

A smooth exit process protects the company’s records, provides employees with appropriate documentation, and ensures that the employment relationship ends with clarity and professionalism.

A good employee journey should include a good beginning—and a professional ending.
24Sep

Employee Document Collection Checklist: What HR Should Verify Before Onboarding

By Nandana G.S , Digital Marketing Executive

Employee onboarding is more than introducing a new employee to the organization. It is also the stage where HR needs to establish accurate employee records, verify essential information, and complete the documentation required for payroll and compliance.

A well-structured document collection process can reduce data errors, prevent payroll issues, and make future HR audits much easier.

1. Personal Information

HR should collect and verify the basic information required to create the employee’s official record.

This may include:

  • Full name

  • Date of birth

  • Contact details

  • Current and permanent address

  • Emergency contact details

  • Other information required under the organization’s onboarding process

HR should ensure that important details are consistent across the documents provided.

2. Identity and Address Verification

Where required and appropriate, HR may collect documents for identity and address verification.

The organization should:

✔️ Collect only documents that are necessary ✔️ Verify information against the relevant records ✔️ Maintain documents securely ✔️ Restrict access to authorized personnel ✔️ Follow applicable privacy and data-protection requirements

HR should avoid collecting unnecessary personal information simply because it is part of an old checklist.

3. Educational and Professional Documents

For roles where qualifications are relevant, HR may verify:

  • Educational certificates

  • Professional certifications

  • Previous employment-related qualifications

  • Professional licenses, where applicable

The level of verification should depend on the role and the organization’s recruitment process.

4. Previous Employment Details

Where applicable, HR should document previous employment information such as:

✔️ Previous employer details ✔️ Designation ✔️ Employment period ✔️ Relevant experience ✔️ Relieving or experience documentation, where required ✔️ Previous employment information needed for payroll/tax purposes

These records can also help HR identify information required for salary and statutory processing.

5. Bank and Payroll Information

Accurate payroll information is essential before the first salary cycle.

HR/payroll should verify the information needed for salary processing, such as:

  • Bank account details

  • Account holder name

  • Required payroll declarations

  • Salary structure and approved compensation details

Incorrect bank or payroll information can result in payment delays and reconciliation issues.

6. PF and UAN Details

For employees covered under applicable EPF requirements, HR should check whether the employee already has a UAN and ensure relevant information is correctly recorded.

HR should:

✔️ Check for an existing UAN ✔️ Avoid unnecessary duplicate UAN creation ✔️ Verify relevant employee details ✔️ Ensure appropriate PF records are linked to the employment ✔️ Coordinate with payroll for accurate contribution processing

7. ESI and Other Statutory Information

Depending on applicability, HR may need to collect or verify information required for ESI, Professional Tax, Labour Welfare Fund, TDS, and other statutory processes.

The exact requirements can vary depending on the employee, establishment, location, salary, and applicable legislation.

Therefore, HR should maintain a state- and organization-specific onboarding checklist rather than using the same checklist for every business.

8. Employment Documentation

Before the employee officially starts, HR should ensure that key employment documents are completed.

These may include:

  • Offer letter

  • Appointment letter

  • Employment agreement, where applicable

  • Job description

  • Compensation details

  • Confidentiality or other agreements, where relevant

  • Employee handbook or policy acknowledgement

The employee should understand the key terms and conditions applicable to the employment.

9. Policy Acknowledgements

Employees should be informed about important workplace policies applicable to them.

Depending on the organization, this may include:

✔️ Code of conduct ✔️ Leave and attendance policy ✔️ POSH policy ✔️ Information security policy ✔️ Work-from-home policy ✔️ Disciplinary policy ✔️ Other company policies

HR should maintain evidence that relevant policies were communicated and acknowledged.

10. Emergency and Contact Information

Emergency contact information should be collected where necessary for workplace administration and employee safety.

HR should ensure that:

  • Contact details are accurate

  • Information is updated when necessary

  • Access is limited to appropriate personnel

11. Background Verification

If the organization conducts background verification, HR should ensure the process is handled consistently and in accordance with applicable requirements.

Depending on the role, verification may cover areas such as:

  • Employment history

  • Educational qualifications

  • References

  • Other role-specific checks

Any required consent and supporting documentation should be maintained appropriately.

12. Create a Standard Onboarding Checklist

Instead of collecting documents randomly, HR can create a standardized onboarding workflow:

Offer → Document Collection → Verification → Employment Documentation → Statutory Setup → Payroll Setup → Policy Acknowledgement → HRMS Entry → Onboarding Completion

Each stage should have a responsible person and a clear completion status.

Common Employee Document Collection Mistakes

HR teams often face problems when they:

❌ Collect documents without verifying them ❌ Request unnecessary personal information ❌ Create duplicate PF/UAN records ❌ Enter inconsistent employee data into HRMS and payroll ❌ Forget policy acknowledgements ❌ Keep incomplete onboarding files ❌ Store employee documents without proper access controls ❌ Fail to update records when employee information changes

Employee Onboarding Document Checklist

A practical checklist can cover:

CategoryWhat HR Should CheckPersonal DetailsName, DOB, contact and addressIdentityRequired identity verificationEducationRelevant qualificationsEmploymentPrevious employment informationPayrollBank and compensation detailsPFUAN/PF information, where applicableStatutoryESI, PT, TDS and other applicable detailsEmploymentOffer/appointment documentationPoliciesRequired policy acknowledgementsVerificationBackground checks, where applicableHRMSAccurate employee master data

How Level Up HR Solutions Can Help

At Level Up HR Solutions, we help businesses create more structured HR systems through HR documentation, employee record management, payroll compliance, statutory compliance, HR audits, and policy support.

A standardized onboarding documentation process helps businesses maintain accurate employee records from Day One and reduces avoidable HR and payroll errors.

Final Thoughts

Employee document collection should not be treated as a routine paperwork exercise. It is an important part of building a reliable employee record and compliance framework.

By collecting only necessary information, verifying it properly, maintaining documents securely, and connecting onboarding with payroll and statutory processes, HR teams can create a smoother and more organized employee experience.

The goal is simple: collect what is necessary, verify what matters, protect employee information, and maintain accurate records.

Level Up HR Solutions 📞 +91 8714805999 📧 info@leveluphrs.com 🌐 www.leveluphrs.com

#EmployeeOnboarding #HRDocumentation #EmployeeRecords #HRCompliance #OnboardingChecklist #PayrollCompliance #HRManagement #StatutoryCompliance #HRIndia #EmployeeOnboardingProcess #KeralaBusiness #KochiBusiness #LevelUpHRSolutions

22Sep

Work From Home Policy: What Should Employers Clearly Define?

By Afla KC , Digital Marketing Executive

Introduction

Work from home has become an important part of modern workplace management. For many organisations, remote work is no longer simply a temporary arrangement. It has become a practical way to offer flexibility, attract talent, improve employee satisfaction, and maintain business continuity.

However, allowing employees to work fro

m home without clear guidelines can create challenges.

Questions can quickly arise:

  • When can employees work from

  •  home?

  • Who is eligible?

  • What are the expected working hours?

  • How should attendance be recorded?

  • How should employees

  • communicate with their teams?

  • Who provides laptops and other equipment?

  • How is employee performance measured?

  • What happens if an em

  • ployee is unavailable during working hours?

A well-designed Work From Home (WFH) Policy provides clarity for both employers and employees. It establishes expectations while giving employees the flexibility to work effectively outside the traditional office environment.

A good policy should not simply say that employees are “allowed to work from home.” It should clearly explain how remote work will operate in practice.

This guide covers the key areas employers should define when creating a work-from-home policy.


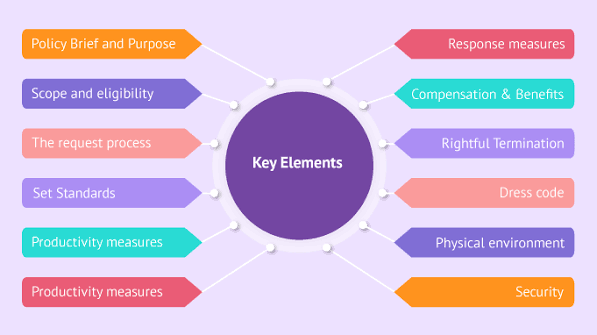
What Is a Work From Home Policy?

A Work From Home Policy is a formal company guideline that explains when and how employees may perform their duties remotely.

It establishes expectations around:

  • Eligibility

  • Working hours

  • Attendance

  • Communication

  • Productivity

  • Performance

  • Technology

  • Data security

  • Expenses

  • Leave

  • Availability

  • Health and safety

  • Policy violations

The purpose is to create a structured remote-working environment rather than leaving expectations open to interpretation.


1. Clearly Define Who Is Eligible

Not every role can necessarily be performed remotely.

Employers should clearly identify which employees or job roles are eligible for work from home.

Eligibility may depend on:

  • Nature of the job

  • Department

  • Employee responsibilities

  • Business requirements

  • Performance

  • Seniority, where applicable

  • Availability of necessary technology

For example, a software developer may be able to work remotely, while a production-floor employee may need to be physically present.

The policy should explain whether WFH is:

  • Available to all eligible employees

  • Available only to selected roles

  • Subject to manager approval

  • Available only in specific circumstances

Clear eligibility criteria can prevent confusion and perceptions of unfair treatment.


2. Define When Work From Home Is Allowed

Employers should specify whether remote work is:

Fully Remote

Employees work from home on a permanent basis.

Hybrid

Employees divide their working time between the office and home.

Occasional WFH

Employees can request remote work for specific days or situations.

Emergency WFH

Employees may work remotely during exceptional circumstances such as severe weather, transportation disruptions, or other emergencies.

The policy should clearly explain which model the organisation follows.


3. Establish Working Hours

Remote work does not mean that working hours become undefined.

Employers should clearly mention:

  • Standard working hours

  • Start and end times

  • Lunch or break periods

  • Core availability hours

  • Shift timings, where applicable

  • Overtime requirements

  • Time-zone expectations for distributed teams

For example, a company may require employees to be available between specific core hours while allowing some flexibility around their start and finish times.

The important point is to create clarity without unnecessarily micromanaging employees.


4. Define Attendance Requirements

Attendance tracking should be clearly addressed.

Employees should know:

  • How attendance is marked

  • Whether login/logout is required

  • How breaks are recorded

  • What happens if there is a technical issue

  • How late attendance is handled

  • How WFH days are recorded

If the organisation uses HRMS or attendance software, the policy should explain the expected process.

A consistent attendance system can also help payroll teams maintain accurate salary and leave records.


5. Explain the WFH Approval Process

Employees should know how to request work from home.

The policy may specify:

  • Who approves WFH

  • How many days can be requested

  • How much advance notice is required

  • Emergency request procedures

  • Documentation requirements, where applicable

For example:

Employee → Reporting Manager → HR, where required

A clearly defined approval workflow prevents informal arrangements from creating administrative problems.


6. Set Communication Expectations

Communication is one of the biggest challenges in remote work.

Employees should know which communication channels are used for different purposes.

For example:

  • Email for formal communication

  • Instant messaging for quick updates

  • Video calls for meetings

  • Project management tools for task tracking

  • HRMS for attendance and leave

The policy can also establish expectations around response times.

For example, employees may be expected to respond to work-related communication during agreed working hours.


7. Define Meeting and Collaboration Rules

Remote employees need to remain connected with their teams.

Employers can establish guidelines around:

  • Online meetings

  • Team calls

  • Camera usage

  • Meeting punctuality

  • Calendar availability

  • Meeting etiquette

  • Internal collaboration

However, organisations should avoid unnecessary meetings.

Remote work is more effective when employees have enough uninterrupted time to complete their actual responsibilities.


8. Set Clear Performance Expectations

One of the biggest misconceptions about remote work is that productivity should be measured by how long an employee appears online.

Instead, organisations should focus on:

  • Deliverables

  • Deadlines

  • Quality of work

  • Goals

  • Customer outcomes

  • Team contribution

Managers should establish measurable performance expectations.

This helps employees understand what they are accountable for while giving them reasonable flexibility in how they complete their work.


9. Define Technology and Equipment Responsibilities

Employers should clearly state who provides the equipment required for remote work.

This may include:

  • Laptop

  • Monitor

  • Keyboard and mouse

  • Headset

  • Internet connection

  • Required software

  • Security tools

The policy should clarify:

  • Who owns company equipment

  • How equipment is maintained

  • What happens if equipment is damaged

  • Whether employees can use personal devices

  • What happens when employment ends

Clear equipment guidelines can prevent disputes later.


10. Address Data Security and Confidentiality

Remote employees may access sensitive company information outside the office.

Therefore, data security should be a major part of any WFH policy.

Employees should be instructed to:

  • Use approved devices

  • Protect passwords

  • Avoid sharing company credentials

  • Use authorised software

  • Secure confidential documents

  • Avoid accessing sensitive information through unsafe networks

  • Report suspected security incidents

Where applicable, organisations should also use tools such as multi-factor authentication, device management, VPNs, and access controls.

The policy should make it clear that company data remains confidential regardless of where the employee works.


11. Explain Internet and Other Work Expenses

Employers should clarify whether they provide or reimburse expenses related to remote work.

Possible expenses include:

  • Internet

  • Mobile communication

  • Electricity

  • Equipment

  • Software subscriptions

  • Other approved work-related costs

If reimbursement is available, the policy should specify:

  • Eligible expenses

  • Maximum limits

  • Required documents

  • Approval process

  • Reimbursement timelines

Avoid vague statements such as “reasonable expenses will be reimbursed” without defining what reasonable means.


12. Include Leave and Absence Rules

Employees working remotely should follow the same applicable leave procedures unless the organisation specifically provides otherwise.

The policy should explain:

  • How leave is requested

  • Who approves leave

  • How emergency leave is communicated

  • How sick leave is reported

  • What happens when an employee becomes unavailable during working hours

Working from home should not be treated as a substitute for applying for leave when an employee is unable to work.


13. Define Health and Safety Expectations

Employers should encourage employees to maintain a safe and suitable home-working environment.

Employees can be advised to:

  • Use an appropriate workstation

  • Maintain good posture

  • Take regular breaks

  • Avoid unsafe work setups

  • Report work-related incidents where required

Depending on the organisation and applicable legal requirements, employers may also consider providing ergonomic guidance or support.


14. Define Geographic Restrictions

Employers should clarify whether employees can work from any location or only from an approved residence.

This is particularly important when employees want to work:

  • From another city

  • From another state

  • From another country

Working from another location can potentially affect taxation, employment compliance, data security, insurance, and other business considerations.

Therefore, employees should obtain approval before changing their regular remote-working location where the policy requires it.


15. Address Employee Privacy

Remote work can create concerns about employee monitoring.

If an organisation uses monitoring software, attendance tracking, device management, or other technology, employees should be informed about:

  • What is monitored

  • Why it is monitored

  • How information is used

  • Who can access it

  • How long relevant information is retained

Employers should aim for transparency and ensure that monitoring practices are consistent with applicable laws and company policies.


16. Define Policy Violations

Employees should understand what happens when WFH rules are repeatedly violated.

Examples may include:

  • Unauthorised absence

  • Misuse of company equipment

  • Sharing confidential information

  • Repeated failure to attend required meetings

  • Misrepresentation of attendance

  • Failure to meet agreed responsibilities

The policy should explain that violations may result in appropriate action under the organisation’s disciplinary procedures.


17. Include Business Continuity Provisions

Remote work policies can also support business continuity.

Employers should explain what happens when:

  • The office becomes unavailable

  • There is a local emergency

  • Employees cannot travel

  • Critical systems are disrupted

  • Certain teams need to operate remotely

Having a predefined process allows organisations to respond faster during unexpected situations.


18. Review the Policy Regularly

A WFH policy should not be treated as a document that is created once and forgotten.

Businesses should review it periodically based on:

  • Changes in workforce structure

  • Technology

  • Employee feedback

  • Business requirements

  • Changes in applicable laws

  • Security requirements

HR teams can also use employee feedback to identify areas where the policy needs improvement.


Common Work From Home Policy Mistakes

Employers should avoid:

Being Too Vague

Statements such as “employees can work remotely when required” create confusion.

Treating Every Role the Same

Different roles may have different operational requirements.

Focusing Only on Attendance

Productivity should not be measured purely by online presence.

Ignoring Data Security

Remote access increases the importance of cybersecurity controls.

Failing to Define Equipment Responsibility

Employees and employers may have different expectations about who pays for equipment and expenses.

Not Defining Approval Procedures

Informal WFH arrangements can create attendance and payroll problems.

Not Communicating the Policy

Even the best policy is ineffective if employees do not understand it.


A Simple Work From Home Policy Checklist

Before implementing a WFH policy, HR teams should confirm that it addresses:

✓ Eligibility

✓ Remote work model

✓ Working hours

✓ Attendance

✓ WFH approval process

✓ Communication

✓ Meetings

✓ Performance expectations

✓ Equipment

✓ Internet and expenses

✓ Data security

✓ Confidentiality

✓ Leave and absence

✓ Health and safety

✓ Geographic restrictions

✓ Employee privacy

✓ Policy violations

✓ Business continuity

✓ Policy review


Conclusion

A successful Work From Home policy is not simply about giving employees permission to work outside the office. It is about creating a clear framework that balances flexibility with accountability.

Employees should understand when they can work remotely, what is expected from them, how they should communicate, how performance will be evaluated, and what responsibilities they have while working from home.

Employers, meanwhile, need clarity around attendance, productivity, equipment, expenses, data security, employee privacy, and compliance.

The most effective WFH policies are clear, practical, flexible, and aligned with the organisation’s actual working environment. They should provide enough structure to maintain productivity and accountability without creating unnecessary restrictions.

As businesses continue to adopt hybrid and remote working models, HR teams should regularly review their policies and ensure that they reflect current business needs and applicable legal requirements.

Ultimately, a well-designed Work From Home policy benefits both sides. Employees gain clarity and flexibility, while employers gain a more structured approach to managing remote teams.

A good WFH policy doesn’t just define where employees work—it defines how people can work effectively, responsibly, and consistently.

21Sep

HR Audit Evidence: What Records and Proof Should Companies Keep Ready?

By Nandana G.S , Digital Marketing Executive

An HR audit is not only about checking whether policies and processes exist. It is also about verifying whether the organization can prove that those processes are being followed.

For businesses, maintaining proper HR records helps demonstrate compliance, identify gaps, support payroll accuracy, and stay prepared for internal reviews, statutory inspections, or employee-related disputes.

What Is HR Audit Evidence?

HR audit evidence refers to the documents, records, reports, approvals, registers, and other supporting proof that demonstrate how an organization’s HR processes are being managed.

Having a policy on paper is one thing. Being able to show evidence of its implementation is another.

1. Employee Personal and Employment Records

HR should maintain accurate records for every employee, including:

✔️ Employee application/resume ✔️ Offer or appointment letter ✔️ Joining documentation ✔️ Employment agreement, where applicable ✔️ Employee master data ✔️ Designation and department records ✔️ Salary and compensation details ✔️ Promotion or transfer records ✔️ Relevant employee declarations and forms

These records should be organized and updated whenever employee information changes.

2. Attendance and Leave Records

Attendance and leave documentation is important for both HR administration and payroll verification.

Companies should maintain:

  • Attendance records

  • Leave applications and approvals

  • Leave balances

  • Late-coming or absence records, where applicable

  • Overtime records, where applicable

  • Working-hours records

The records should be consistent with the information used for payroll processing.

3. Payroll and Salary Records

Payroll is one of the key areas reviewed during an HR audit.

Evidence may include:

✔️ Salary registers ✔️ Payroll processing reports ✔️ Payslips ✔️ Salary structure records ✔️ Deductions and recoveries ✔️ Overtime or incentive calculations ✔️ Full & Final settlement records ✔️ Payroll reconciliation reports

HR and payroll teams should be able to explain significant variations or adjustments.

4. Statutory Compliance Records

Companies should maintain appropriate evidence relating to applicable statutory requirements.

Depending on the organization’s applicability, this may include records relating to:

  • PF

  • ESI

  • Professional Tax

  • TDS

  • Labour Welfare Fund

  • Gratuity

  • Applicable labour-law registers and returns

  • Statutory payments and acknowledgements

The exact records required can vary based on the organization’s location, workforce, and applicable laws.

5. HR Policies and Employee Acknowledgements

Having policies is not enough. Organizations should also maintain evidence that employees have been informed about relevant policies.

Examples include:

✔️ Employee handbook ✔️ Leave policy ✔️ Attendance policy ✔️ Code of conduct ✔️ POSH policy ✔️ Work-from-home policy ✔️ Disciplinary policy ✔️ Policy acknowledgement records

Whenever policies are updated, HR should maintain appropriate communication and acknowledgement records.

6. Recruitment and Onboarding Records

An HR audit may also examine whether recruitment and onboarding processes are properly documented.

Keep records such as:

  • Job descriptions

  • Interview evaluation forms

  • Selection approvals

  • Offer letters

  • Joining checklists

  • Onboarding documentation

  • Employee induction records

  • Background verification records, where applicable

A standardized recruitment file can make the audit process much easier.

7. Performance Management Records

Performance-related decisions should have supporting documentation.

HR may maintain:

✔️ Performance appraisal records ✔️ Goal-setting documents ✔️ Performance review forms ✔️ Feedback records ✔️ Performance improvement plans ✔️ Promotion recommendations ✔️ Increment approvals

Proper documentation can help demonstrate that employment decisions were based on an established process.

8. Training and Development Records

Organizations should maintain evidence of employee development activities.

This can include:

  • Training calendars

  • Attendance records

  • Training completion certificates

  • Skill development records

  • Training feedback

  • POSH awareness/training records

  • Other mandatory or role-specific training records

9. Disciplinary and Grievance Records

Where disciplinary or grievance matters arise, HR should maintain appropriate documentation.

Depending on the situation, this may include:

  • Employee complaints

  • Written explanations

  • Show-cause notices

  • Warnings

  • Investigation records

  • Management decisions

  • Grievance resolution records

These records should be handled with appropriate confidentiality and access controls.

10. Employee Exit Documentation

The employee exit process should also have a complete documentation trail.

HR should maintain:

✔️ Resignation letter/email ✔️ Resignation acceptance ✔️ Notice-period records ✔️ Handover documentation ✔️ Clearance records ✔️ Asset-return confirmation ✔️ Exit interview, where conducted ✔️ Full & Final settlement ✔️ Relieving and experience documents

A properly documented exit process can help reduce misunderstandings after separation.

11. HR Audit Trail and Approvals

One commonly overlooked area is proof of approvals and decision-making.

Organizations should retain appropriate evidence such as:

  • Management approvals

  • Salary revision approvals

  • Leave approvals

  • Hiring approvals

  • Policy approvals

  • Exception approvals

  • HR communications

  • Relevant email trails

This helps auditors understand not just what happened, but who authorized it and when.

12. Digital Records and Access Control

Modern HR departments increasingly rely on digital HRMS and payroll systems.

Companies should ensure that digital records are:

✔️ Properly organized ✔️ Backed up ✔️ Accessible to authorized personnel ✔️ Protected from unauthorized access ✔️ Retained according to applicable requirements

Important documents should not exist only in individual employees’ personal email accounts or local computer folders.

Common HR Audit Evidence Gaps

Businesses often face problems because they:

❌ Have policies but no acknowledgement records ❌ Maintain incomplete employee files ❌ Have payroll records that don’t match HR records ❌ Cannot produce approval trails ❌ Maintain inconsistent attendance and leave data ❌ Miss statutory payment or filing evidence ❌ Store documents across disconnected systems ❌ Fail to maintain proper exit documentation

HR Audit Evidence Checklist

A simple audit-ready HR file structure can include:

Employee Records → Recruitment → Onboarding → Attendance & Leave → Payroll → Statutory Compliance → Policies → Performance → Training → Grievances → Disciplinary Records → Exit Documentation → Approvals & Audit Trail

The goal is not to create paperwork for the sake of paperwork. The goal is to ensure that every important HR process has reliable supporting evidence.

How Level Up HR Solutions Can Help

At Level Up HR Solutions, we help businesses strengthen their HR systems through HR audits, HR documentation, payroll compliance, statutory compliance reviews, employee record management, and policy support.

An HR audit can help identify documentation gaps before they become larger compliance or operational problems.

Final Thoughts

Being audit-ready means more than having a collection of HR documents. Companies need a structured system where records are accurate, updated, traceable, and easy to retrieve.

When HR teams maintain proper evidence throughout the employee lifecycle, they can improve compliance, strengthen internal controls, and respond more confidently to audits and inspections.

Start building your HR audit file before you need it—not when an audit arrives.

Level Up HR Solutions 📞 +91 8714805999 📧 info@leveluphrs.com 🌐 www.leveluphrs.com

#HRAudit #HRAuditChecklist #HRCompliance #HRDocumentation #PayrollCompliance #StatutoryCompliance #EmployeeRecords #HRManagement #HRIndia #AuditReady #KeralaBusiness #KochiBusiness #LevelUpHRSolutions

18Sep

Old vs New Tax Regime: What Employers Need to Consider While Processing Payroll

by Naziha , Digital Marketing Executive

Processing employee salaries is not just about calculating gross pay and transferring the final amount to an employee’s bank account. One of the most important responsibilities for employers and payroll teams is calculating and deducting the correct amount of Tax Deducted at Source (TDS).

With employees having a choice between the old and new tax regimes, payroll processing has become more complex. HR and payroll teams must understand the employee’s tax regime, consider eligible deductions and exemptions, calculate projected annual taxable income, and ensure that monthly TDS is deducted correctly.

A wrong tax calculation can create problems for both the employer and the employee. Employees may face unexpected tax deductions or refunds, while employers may face payroll corrections and compliance issues.

For the 2026–27 tax year, payroll teams also need to ensure that their systems and processes reflect the applicable tax rules for the relevant period.

This guide explains the key differences between the old and new tax regimes and what employers should consider while processing employee payroll.


Understanding the Old and New Tax Regimes

India currently provides different tax structures for eligible individual taxpayers.

The new tax regime is the default regime, while eligible taxpayers can choose to opt for the old regime. The two regimes differ mainly in their tax rates and the availability of deductions and exemptions.

The old regime generally provides access to a wider range of deductions and exemptions, while the new regime generally offers different tax slabs and allows only limited deductions and exemptions.

For employers, this means payroll processing cannot follow a one-size-fits-all approach.


What Is the Old Tax Regime?

The old tax regime follows the traditional tax structure.

Under this regime, employees may be able to claim various eligible tax deductions and exemptions, subject to applicable conditions and limits.

Common examples may include:

  • House Rent Allowance (HRA), subject to applicable conditions

  • Leave Travel Allowance (LTA), where eligible

  • Certain deductions relating to investments

  • Eligible insurance-related deductions

  • Eligible deductions for specified expenses

  • Home loan-related tax benefits, where applicable

Because more deductions and exemptions may be available, the old regime can be beneficial for some employees who have significant eligible tax-saving investments or exemptions.

However, payroll teams must collect and verify the required declarations and supporting documents where necessary.


What Is the New Tax Regime?

The new tax regime is the default tax regime for eligible taxpayers.

It generally provides a different tax slab structure while allowing fewer deductions and exemptions compared with the old regime.

Under the official slab information available for AY 2026–27, the new regime for most individual taxpayers uses the following slab structure:

Taxable IncomeTax RateUp to ₹4 lakhNil₹4 lakh – ₹8 lakh5%₹8 lakh – ₹12 lakh10%₹12 lakh – ₹16 lakh15%₹16 lakh – ₹20 lakh20%₹20 lakh – ₹24 lakh25%Above ₹24 lakh30%

These rates are subject to applicable provisions, rebate rules, surcharge, and Health and Education Cess.

The lower or differently structured tax rates may benefit employees who do not have substantial deductions or exemptions available under the old regime.


Old Tax Regime vs New Tax Regime: A Quick Comparison

FactorOld Tax RegimeNew Tax RegimeDefault regimeNoYesTax slabsTraditional slab structureRevised slab structureDeductionsMore deductions may be availableLimited deductionsExemptionsSeveral exemptions may be availableMany exemptions are restrictedInvestment declarationsOften important for tax calculationDepends on eligible deductionsBest optionDepends on employee’s deductions and exemptionsDepends on employee’s income and tax position

There is no single regime that is automatically best for every employee.

The better option depends on factors such as:

  • Annual income

  • Eligible deductions

  • Eligible exemptions

  • Investments

  • Salary structure

  • Other taxable income

The Income Tax Department itself advises taxpayers to compare the tax liability under both regimes before making a decision.


1. Collect the Employee’s Tax Regime Intimation

One of the first things employers should do is obtain the employee’s intended tax regime for payroll purposes.

According to Income Tax Department guidance, an employee should intimate the employer regarding their intended tax regime during the year. If the employee does not provide an intimation, the employer generally treats the employee under the default new tax regime for TDS purposes.

Best practice for employers

At the beginning of the financial year, provide employees with a clear process to:

  • Select their intended tax regime for payroll purposes

  • Submit required declarations

  • Provide relevant information for TDS calculations

This helps payroll teams avoid incorrect assumptions.


2. Do Not Treat Every Employee the Same

A common payroll mistake is assuming that all employees should be processed under the same tax regime.

Employees have different financial situations.

For example:

Employee A

May have:

  • Significant eligible investments

  • Eligible HRA exemptions

  • Other applicable deductions

The old regime may potentially be more favourable.

Employee B

May have:

  • Few tax-saving investments

  • Limited exemptions

  • A relatively simple salary structure

The new regime may potentially result in a better tax outcome.

Employers should not recommend a regime without considering the individual’s circumstances. Their primary responsibility is to process payroll correctly based on the applicable rules and employee declarations.


3. Understand the Impact on Investment Proof Collection

The old and new regimes can significantly affect how HR teams collect investment declarations and proofs.

Under the old tax regime, employee declarations and eligible supporting documents may be important for calculating deductions and exemptions.

Payroll teams may need to process information relating to eligible:

  • Investments

  • Insurance payments

  • Rent details

  • Other deductions

  • Applicable exemptions

Under the new regime, many traditional deductions and exemptions are not available, although certain specified benefits may still be permitted under applicable tax provisions.

This can reduce the number of investment proofs required for some employees.

However, employers should not assume that no declarations are ever required under the new regime. The payroll team must consider deductions or exemptions that remain available under the applicable rules.


4. Calculate TDS Based on Projected Annual Income

Salary TDS should not simply be calculated by applying a tax percentage to one month’s salary.

Employers generally need to estimate the employee’s projected taxable income for the relevant tax year.

The calculation may include:

  • Monthly salary

  • Bonus payments

  • Incentives

  • Arrears

  • Other taxable benefits

  • Eligible exemptions

  • Applicable deductions

Once projected taxable income is determined, the employer can calculate the estimated annual tax liability and distribute the TDS appropriately across the remaining payroll months.

This is particularly important when an employee receives:

  • A salary increment

  • A bonus

  • A promotion

  • Variable pay

  • Additional taxable benefits


5. Update TDS When Salary Changes

Employee tax calculations should not remain unchanged throughout the year if the employee’s income changes.

For example, an employee may receive:

  • A salary increase

  • Annual bonus

  • Performance incentive

  • Sales commission

  • Arrears

These changes can increase projected annual income and affect the employee’s tax liability.

Payroll teams should review TDS calculations periodically rather than waiting until the end of the financial year.


6. Handle New Joiners Carefully

When a new employee joins an organization during the financial year, their current employer may need information about salary received from previous employment.

Without considering previous salary income, the employer may calculate TDS only on the salary paid by the current organization, potentially resulting in incorrect overall tax deductions.

HR and payroll teams should have a structured process for collecting relevant previous employment and salary information where required for accurate TDS processing.


7. Keep Accurate Employee Declarations and Records

Payroll compliance depends heavily on documentation.

Employers should maintain appropriate records relating to:

  • Employee tax regime intimation

  • Salary declarations

  • Investment declarations

  • Supporting documents, where applicable

  • Previous employment income information

  • Tax calculations

  • TDS deductions

Proper documentation can help organizations explain and support payroll calculations if questions arise later.


8. Understand That the New Regime Is the Default for Payroll Purposes

The new tax regime is the default regime under the applicable framework.

If an employee does not intimate their intended choice to the employer for the relevant year, the employer generally deducts TDS based on the default new tax regime.

This makes employee communication extremely important.

A simple annual email or HR portal declaration can help reduce confusion.


9. Employees May Have Different Options at the Return Stage

Employers should understand the difference between:

  • TDS processing during the year, and

  • The employee’s final tax position when filing their income tax return

For eligible individuals without business or professional income, the option relating to the tax regime may generally be exercised according to the applicable rules when filing the income tax return.

The employer’s payroll calculation is based on the information and regime intimation provided for TDS purposes during the year.

This is why employees should understand that payroll TDS and final tax return filing are related but should not always be treated as identical processes.


10. Update Payroll Systems for Current Tax Rules

Tax rules and administrative provisions can change.

For 2026–27, the Income Tax Department has specifically advised employers to reset TDS computation from 1 April 2026 for the new tax year, considering projected income, deductions, and the applicable tax regime. Payroll systems also need to reflect the relevant legislative and section-numbering changes applicable to the new tax year.

Payroll teams should ensure that:

  • Tax slabs are updated

  • TDS formulas are reviewed

  • The correct tax year is selected

  • Regime options are configured properly

  • Payroll software reflects current requirements

Using outdated payroll settings can result in incorrect deductions for every employee.


Common Payroll Mistakes Employers Should Avoid

1. Automatically Applying the Same Regime to Everyone

Employees may have different tax situations.

Always obtain the required regime intimation and process TDS accordingly.


2. Using Outdated Tax Slabs

Tax slabs can change from one tax year to another.

Payroll software should be reviewed at the beginning of every financial year.


3. Ignoring Employee Investment Declarations

For employees using the old regime, eligible declarations and supporting information can significantly affect taxable income.


4. Forgetting Salary Revisions

A salary increment or bonus can change projected annual tax liability.

TDS should be recalculated when necessary.


5. Not Considering Previous Employment Income

New employees may already have received taxable salary from another employer during the same year.


6. Waiting Until the Last Month to Correct TDS

Waiting until the end of the year can result in a large and unexpected TDS deduction from the employee’s final salaries.

Periodic reviews are much better.


A Simple Payroll Checklist for HR Teams

Before finalizing payroll, HR and payroll teams should check:

✔ Has the employee provided their tax regime intimation?

✔ Is the default regime being applied correctly where no intimation has been provided?

✔ Are the current tax slabs configured correctly?

✔ Has projected annual income been calculated?

✔ Have salary increments and bonuses been considered?

✔ Are applicable deductions and exemptions processed correctly?

✔ Have required declarations and documents been collected?

✔ Has previous employment income been considered where necessary?

✔ Has monthly TDS been reviewed and adjusted?

✔ Are payroll records securely maintained?


How Technology Can Simplify Tax Regime Management

Modern payroll systems can help employers manage tax compliance by:

  • Allowing employees to select a tax regime

  • Collecting declarations digitally

  • Tracking investment submissions

  • Calculating projected tax liability

  • Automatically adjusting TDS

  • Generating payroll reports

  • Maintaining employee records

However, automation should always be supported by regular payroll reviews.

Incorrect system configuration can automate errors just as efficiently as it automates correct calculations.


Final Thoughts

The choice between the old and new tax regimes has made payroll processing more important than simply calculating monthly salary.

Employers need a structured process to collect employee tax regime information, calculate projected annual income, process eligible deductions and exemptions, and review TDS regularly throughout the year.

The new tax regime is the default, but the most suitable regime can vary depending on an employee’s income, deductions, and exemptions.

For HR and payroll teams, the goal is not to decide which tax regime is universally better. The goal is to ensure that payroll calculations are accurate, employee declarations are properly recorded, and TDS is processed according to the latest applicable rules.

By maintaining updated payroll systems, communicating clearly with employees, and reviewing TDS throughout the year, employers can reduce errors and make tax compliance significantly easier.

When tax rules or an employee’s circumstances are complex, organizations should verify the latest official guidance or seek advice from a qualified tax professional before making payroll decisions.

17Sep

EPFO Wage Ceiling Hike: What the Increase from ₹15,000 to ₹25,000 Means for Employers and Employees

Published by Level Up HR Solutions | Payroll & Compliance Insights

In a major labour law development, the Union Cabinet has approved raising the EPFO wage ceiling from ₹15,000 to ₹25,000 per month, effective from the date of the official notification. The decision, cleared under the Ministry of Labour & Employment, is expected to bring over 51 lakh additional employees under mandatory Employees’ Provident Fund Organisation (EPFO) coverage — one of the most significant social security reforms since the ceiling was last revised in 2014.

If you’re an HR professional, payroll manager, or business owner, this change directly affects how you structure salaries, compute statutory deductions, and plan compliance going forward. Here’s a complete breakdown.

Note: Not Yet Officially Implemented
As of now, this is a Cabinet-approved decision, not a notified law. The Ministry of Labour & Employment is yet to issue the official gazette notification specifying the effective date and implementation guidelines. Employers should treat this as an upcoming change to prepare for, and should wait for the formal notification before altering payroll structures or contribution calculations.

What Exactly Has Changed?

Previously, an employee joining a job at a monthly wage above ₹15,000 was not automatically brought under mandatory EPF coverage — employers had discretion in many such cases. With the ceiling now raised to ₹25,000, every employee earning up to this threshold will fall within the statutory ambit of EPF, the Employees’ Pension Scheme (EPS), and the Employees’ Deposit Linked Insurance Scheme (EDLI).

For context: the wage ceiling stayed unchanged for a full decade (2004–2014) before being revised to ₹15,000 in September 2014. This new hike to ₹25,000, more than a decade later, is meant to catch up with rising wage levels and the expansion of formal employment across India.

Why This Matters: The Bigger Picture

The government has positioned this move as a step toward strengthening formalisation of the workforce and advancing India’s long-term social security vision under the Viksit Bharat@2047 goal. In practical terms, it means a much larger share of India’s salaried workforce — especially those in the ₹15,000–₹25,000 wage band — will now have access to structured retirement savings, pension protection, and insurance cover that they may currently be missing out on.

Pros of the EPFO Wage Ceiling Hike

  1. Wider social security net — The most immediate benefit is scale — over 51 lakh employees who were previously outside mandatory coverage will now be entitled to PF savings, pension benefits under EPS, and insurance protection under EDLI.
  2. Better retirement planning for mid-income earners — Employees in the ₹15,000–₹25,000 bracket, who often fall in a grey zone, gain access to a disciplined, employer-matched retirement savings mechanism.
  3. Boost to formal employment — Because coverage is now mandatory for a larger wage band, employers have less room to structure roles to stay below the ceiling — pushing more jobs into the formal, compliant economy.
  4. Enhanced insurance protection — Coverage under EDLI means eligible employees’ families gain a layer of life insurance protection linked to their PF account, at no direct cost to the employee.
  5. Alignment with rising wage levels — With inflation and wage growth over the past decade, ₹15,000 no longer reflected realistic entry- or mid-level salaries in many sectors.

Cons and Challenges to Watch

  1. Higher payroll cost for employers — A larger pool of employees now qualifying for mandatory EPF contributions means increased employer-side contribution liability, which could raise overall payroll costs — particularly for SMEs with thin margins.
  2. Reduced take-home pay for some employees — Employees who move to mandatory EPF status may see a higher portion of their salary diverted to PF contributions, reducing immediate in-hand income.
  3. Compliance and administrative burden — HR and payroll teams will need to re-evaluate every employee earning ₹15,000–₹25,000, update UAN registrations, revise CTC structures, and ensure timely compliance.
  4. Potential restructuring of CTC — Some employers may respond by restructuring compensation to manage the cost impact, which could lead to short-term confusion if not communicated transparently.
  5. Sector-specific strain — Labour-intensive sectors with thin margins — retail, textiles, small-scale manufacturing — may feel a proportionally larger cost impact.

What Should Employers Do Now?

  • Review current payroll data to identify employees who will newly fall under mandatory EPF coverage.
  • Recalculate projected employer contribution costs for FY planning.
  • Update HRMS and payroll systems ahead of the formal notification/effective date.
  • Communicate the change clearly to affected employees, framing it as a long-term benefit.
  • Consult with compliance/payroll experts to ensure a smooth transition without penalties.

The Takeaway

The EPFO wage ceiling hike from ₹15,000 to ₹25,000 is one of the most consequential labour law updates in over a decade. While it brings clear long-term benefits — wider retirement coverage, stronger insurance protection, and greater formalisation — it also brings real, near-term compliance and cost challenges for businesses.

For organisations navigating this transition, having the right payroll and compliance partner makes all the difference. Level Up HR Solutions helps businesses stay ahead of exactly these kinds of regulatory changes — from payroll restructuring to statutory compliance management — so you can focus on your people, not paperwork.

Need help assessing how this change impacts your payroll? Get in touch with Level Up HR Solutions for a compliance review.


Source: Press Information Bureau (PIB), Ministry of Labour & Employment, Government of India — Posted 16 Sep 2026.

17Sep

Employee Joins or Leaves Mid-Month: How Does Professional Tax Deduction Work?

Introduction

Professional Tax is a statutory deduction that often creates confusion for HR and payroll teams, especially when an employee joins or leaves an organisation in the middle of a month.

Unlike income tax, Professional Tax is a state-level tax. The applicable rate, salary threshold, payment frequency, exemptions, and calculation method depend on the state in which the employee is working. Therefore, there is no single nationwide formula that can be applied to every employee.

One of the most common payroll questions is:

“If an employee works only part of a month, should Professional Tax still be deducted?”

The answer depends on the applicable state’s Professional Tax legislation and the specific rules used to determine liability.

For HR teams, this becomes particularly important during employee onboarding, full-and-final settlement, payroll processing, transfers, and monthly statutory compliance.

In this guide, we will explain how Professional Tax generally works when an employee joins or leaves mid-month, what payroll teams should check, common mistakes to avoid, and how organisations can make PT processing more accurate.


What Is Professional Tax?

Professional Tax is a tax imposed by state governments on individuals engaged in professions, trades, callings, or employment.

For salaried employees, the employer generally deducts the applicable Professional Tax from salary and deposits it with the relevant state authority or local body.

The tax is not the same as income-tax TDS.

Professional Tax is:

  • State-specific

  • Governed by applicable state legislation

  • Usually linked to salary or income slabs

  • Deducted by employers from eligible employees

  • Subject to state-specific exemptions and rules

For example, Karnataka’s official Professional Tax portal states that employers are responsible for deducting and paying Professional Tax for eligible employees according to the applicable slab.


Why Mid-Month Joining Creates Confusion

Suppose an employee joins a company on the 15th of the month.

They don’t receive their full monthly salary because they have worked only part of the month.

For example:

Monthly salary: ₹40,000

Days worked: 15

Salary paid for the month: approximately ₹20,000

The question then becomes:

Should Professional Tax be calculated on ₹40,000 or ₹20,000?

There is no universal answer.

The payroll team must check the Professional Tax rules applicable in the relevant state, including how the salary slab and liability are determined.

This is why HR teams should not automatically apply a standard “pro-rata PT” rule to every employee.


Professional Tax Is State-Specific

This is the first rule HR teams should remember.

Professional Tax is not administered through one uniform national slab.

Different states can have different:

  • Salary thresholds

  • Tax slabs

  • Deduction amounts

  • Payment frequencies

  • Exemptions

  • Registration requirements

  • Calculation methods

For example, Karnataka currently provides a monthly exemption threshold for salaried employees below the prescribed salary limit, with the applicable slab determined under Karnataka’s Professional Tax rules.

Kerala follows a different framework, with profession tax administered through the applicable local-body/state system and collected from eligible employees.

Therefore, HR teams should always begin with:

Which state and local authority’s Professional Tax rules apply to this employee?


When an Employee Joins Mid-Month

Consider an employee who joins on 16 August.

Their monthly salary is ₹35,000, but because they joined in the middle of the month, they receive only a proportionate salary for August.

The payroll team should determine:

  1. The employee’s applicable work location.

  2. Whether the employee is liable for Professional Tax.

  3. Which salary amount is relevant under the applicable state rules.

  4. Whether the state uses monthly, half-yearly, or another assessment/payment mechanism.

  5. Whether any exemption applies.

  6. Whether the employee’s employment duration affects liability.

Only after checking these factors should the payroll team calculate the deduction.


Does Joining Mid-Month Automatically Mean No Professional Tax?

No.

A common payroll misconception is that an employee who works only part of a month is automatically exempt from Professional Tax.

That is not necessarily correct.

Some states or local authorities may determine liability based on the applicable salary/income slab and prescribed rules, while others may have different assessment or collection mechanisms.

Therefore:

Mid-month joining ≠ automatic PT exemption.

The applicable state legislation should determine the treatment.


Example: Mid-Month Joiner

Imagine an employee has:

Monthly salary: ₹50,000

Joining date: 20 August

Because the employee worked only part of August, their actual salary payment for August may be substantially lower than their full monthly salary.

The payroll team should not simply assume:

“Salary is below the PT threshold this month, so PT is zero.”

Instead, payroll should check the applicable state’s rules to determine whether the threshold is based on the actual salary paid for that period or another prescribed basis.

This distinction can prevent incorrect deductions.


When an Employee Leaves Mid-Month

The same issue occurs when an employee resigns or is terminated during the month.

Suppose an employee leaves on 12 September.

Their normal monthly salary is ₹45,000, but their final month’s salary is calculated only for the days worked.

The payroll team must determine the applicable Professional Tax treatment before processing the employee’s final salary.

This is particularly important because the final payroll may include:

  • Salary for days worked

  • Leave encashment

  • Overtime

  • Incentives

  • Other eligible payments

  • Deductions

  • Full-and-final settlement amounts

The treatment of each component may depend on the applicable rules.


Professional Tax During Full and Final Settlement

Full-and-final settlement is an important area for HR teams.

When an employee leaves, payroll should review all statutory deductions before releasing the final settlement.

The organisation should verify:

  • Outstanding Professional Tax

  • Applicable PT for the relevant period

  • Salary payable

  • Leave-related payments

  • Other statutory deductions

  • Final payroll records

Kerala’s profession-tax rules, for example, specifically provide for recovery of profession tax in certain employee-relieving situations, demonstrating why exit payroll should be checked against the applicable local rules rather than handled using a generic formula.


Monthly vs Half-Yearly Professional Tax

Another important factor is the frequency with which Professional Tax is assessed or collected.

Not every state follows exactly the same mechanism.

For example, the official Kerala Professional Tax portal states that profession tax is paid on a semi-annual basis under the applicable system.

In contrast, Karnataka operates a monthly deduction/payment structure for employee Professional Tax.

This difference can significantly affect how HR teams handle employees who join or leave during a particular month.

Therefore, payroll teams should not assume that a monthly calculation method applies across all states.


What If an Employee Works in One State but Is Paid From Another?

This situation is common for companies with headquarters in one state and branches in several others.

For Professional Tax purposes, the employee’s place of work can be important.

For example, Karnataka’s official Professional Tax FAQ states that where a company is registered in another state but employees work in Karnataka, the Professional Tax is payable in the state where the employees are working, irrespective of where salary is disbursed.

Therefore, payroll teams should maintain accurate employee work-location information.


What HR Teams Should Check for Mid-Month Joiners

Before processing PT for a new employee, HR/payroll teams should verify:

1. Employee Work Location

Identify the state and relevant local authority.

2. Salary Details

Check the applicable salary or wage information.

3. PT Registration

Confirm that the employer has the required Professional Tax registration where applicable.

4. State Slab

Review the current applicable Professional Tax slab.

5. Exemptions

Check whether the employee falls under any prescribed exemption.

6. Joining Date

Record the exact date the employee started work.

7. Payroll Amount

Check the salary actually payable for the relevant period.

8. Assessment Method

Determine whether the applicable state uses monthly, half-yearly, or another prescribed method.


What HR Teams Should Check for Employees Leaving Mid-Month

For an employee leaving during the month, payroll should verify:

  • Last working date

  • Salary payable for the month

  • Applicable PT liability

  • Previous PT deductions

  • Outstanding statutory deductions

  • Full-and-final settlement

  • Required statutory records

  • PT payment and reporting requirements

A final payroll checklist can prevent missed deductions or incorrect recovery.


Common Professional Tax Mistakes

1. Applying One State’s Rule Everywhere

A company operating across India may have employees subject to different PT rules.

Using one generic slab can create errors.

2. Automatically Pro-Rating PT

Not every state follows the same pro-rata calculation method.

3. Ignoring Work Location

Professional Tax is linked to state-level rules, so employee work location matters.

4. Missing State-Specific Exemptions

Some states provide exemptions for specific categories of employees.

5. Using Outdated Slabs

PT slabs and requirements can change through state notifications.

6. Incorrect Full-and-Final Processing

The final month should be reviewed carefully before releasing settlement.


How Payroll Software Can Help

Professional Tax calculations can become complicated when an organisation has employees across multiple states.

Payroll software can help HR teams manage:

  • Employee work locations

  • State-specific PT rules

  • Salary calculations

  • Mid-month joining

  • Mid-month exits

  • Statutory deductions

  • Payroll reports

  • Full-and-final settlement

  • Compliance records

Automation can reduce repetitive calculations and minimise manual errors.

However, payroll software must be configured with the correct and current state-specific rules.

Technology can automate a calculation, but it cannot compensate for an incorrect statutory configuration.


A Simple Payroll Workflow

HR teams can follow this process for every employee:

Step 1: Identify the employee’s work state.

Step 2: Confirm whether Professional Tax applies.

Step 3: Check the current state-specific slab and exemptions.

Step 4: Review the employee’s joining or leaving date.

Step 5: Determine the salary applicable for the relevant period.

Step 6: Apply the prescribed calculation method.

Step 7: Deduct PT through payroll where applicable.

Step 8: Record and remit the deduction according to the required timeline.

Step 9: Review the payroll before final submission.

This process creates consistency and reduces the risk of missed statutory deductions.


Professional Tax Compliance Checklist

For HR and payroll teams:

✓ Confirm the employee’s work location

✓ Identify the applicable state PT law

✓ Check the current salary slab

✓ Verify applicable exemptions

✓ Check joining/exit date

✓ Determine the applicable assessment method

✓ Calculate PT according to state rules

✓ Deduct the correct amount

✓ Maintain payroll records

✓ Remit PT within the prescribed timeline

✓ Complete required returns or filings

✓ Review full-and-final settlements


Conclusion

Professional Tax deduction becomes particularly important when an employee joins or leaves in the middle of a month. While it may appear to be a simple payroll deduction, the actual treatment can depend on state-specific legislation, salary slabs, exemptions, assessment periods, work location, and the employee’s employment dates.

The most important point for HR teams is that there is no single Professional Tax rule that applies uniformly across India. Each state that levies Professional Tax can prescribe its own framework. Kerala, Karnataka, Maharashtra, and other states may therefore require different payroll approaches.

HR teams should avoid automatically pro-rating or waiving Professional Tax simply because an employee worked only part of a month. Instead, payroll should check the applicable state rules, determine the correct basis of liability, and ensure that deductions and statutory payments are accurately recorded.

For organisations with employees across multiple locations, a state-wise Professional Tax matrix combined with reliable payroll software can make compliance significantly easier.

Ultimately, accurate Professional Tax processing is about more than getting one payroll deduction right. It is about maintaining a consistent, transparent, and compliant payroll system that protects both the organisation and its employees.

Important note: Professional Tax rules, slabs, exemptions, assessment periods, and procedures vary by state and may change through government notifications. HR teams should verify the latest applicable

state rules before processing payroll. 

16Sep

PF UAN Management: What HR Teams Need to Do for New Employees

By Nandana G.S , Digital Marketing Executive

When a new employee joins an organization, PF compliance should begin from the onboarding stage itself. One of the most important parts of this process is ensuring that the employee’s Universal Account Number (UAN) is correctly identified, linked, and maintained.

A UAN provides a unified identity for an employee’s EPF accounts across different employments. For HR and payroll teams, proper UAN management helps avoid duplicate accounts, incorrect member details, and unnecessary compliance issues.

1. Check Whether the Employee Already Has a UAN

Before creating or processing a new PF account, HR should determine whether the employee already has a UAN from previous employment.

The employee may have an existing UAN even if they have changed:

  • Employer

  • Job role

  • Location

  • Industry

  • Organization

HR should avoid creating duplicate UANs unnecessarily.

2. Collect Accurate Employee Information

During onboarding, HR should collect and verify the information required for PF-related processing.

Important details may include:

✔️ Employee name ✔️ Date of birth ✔️ Aadhaar details as applicable ✔️ Bank account information ✔️ Mobile number ✔️ Existing UAN, if available ✔️ Previous employment details, where relevant

The information submitted for PF records should match the employee’s supporting records.

3. Verify UAN and KYC Details

HR/payroll teams should ensure that the employee’s UAN-related information and KYC records are properly maintained.

Depending on the applicable EPFO process, this may involve verification of:

  • Aadhaar

  • Bank account

  • PAN, where applicable

  • Mobile number

  • Name and date-of-birth details

Incorrect information can create difficulties when employees later try to access or transfer their PF benefits.

4. Link the Employee Correctly With the New Employer

For an employee who already has a UAN, the new employment should be associated with the existing UAN rather than unnecessarily creating another identity.

HR should carefully verify the employee’s existing UAN and ensure the correct PF member/employment details are processed.

5. Handle New Employees Without an Existing UAN

If an eligible employee does not have a UAN, HR/payroll should follow the applicable EPFO process for UAN generation/allocation.

The process and authentication requirements may change over time, so HR teams should follow the latest EPFO instructions and employer portal procedures.

6. Ensure Correct PF Wage and Contribution Processing

UAN management is only one part of PF compliance.

Payroll teams should also ensure that:

✔️ PF wages are correctly determined ✔️ Employee contributions are accurately calculated ✔️ Employer contributions are correctly processed ✔️ Monthly ECR information is accurate ✔️ Contributions are remitted within the applicable timelines ✔️ Employee records are reconciled with payroll

A correct UAN does not compensate for incorrect PF calculations or payroll data.

7. Avoid Duplicate or Incorrect Employee Records

One of the common HR challenges is inconsistent information across employee records.

For example, differences in an employee’s name, date of birth, Aadhaar details, or other identifying information can cause problems with PF-related services.

HR should establish a verification step during onboarding rather than waiting until the employee faces an issue.

8. Maintain Proper Documentation

HR should maintain an organized record of PF/UAN onboarding information.

A practical checklist can include:

Employee Joining → PF Eligibility Check → Existing UAN Verification → Employee Details Verification → KYC Review → Employer/Member Record Setup → Payroll Mapping → ECR/Reconciliation → Record Maintenance

This creates a structured process for every new employee.

Common PF UAN Management Mistakes

HR teams should watch out for:

❌ Creating duplicate UANs ❌ Entering incorrect employee details ❌ Failing to verify an existing UAN ❌ Incomplete KYC information ❌ Incorrect PF wage mapping ❌ Payroll and PF records not matching ❌ Delayed correction of employee information ❌ Lack of onboarding documentation

Why UAN Management Matters for Employees

Proper UAN management makes it easier for employees to manage their PF-related records across different employments.

For employers, accurate UAN and PF records support better payroll administration, statutory compliance, reconciliation, and audit readiness.

How Level Up HR Solutions Can Help

At Level Up HR Solutions, we help businesses manage their HR and payroll processes with greater accuracy through payroll compliance, PF/ESI compliance support, HR documentation, statutory compliance reviews, and HR audits.

A strong PF onboarding process helps businesses reduce avoidable errors and ensures employee records remain organized from the beginning of employment.

Final Thoughts

PF UAN management should not be treated as a one-time onboarding formality. It should be part of a standardized HR and payroll process that includes verification, accurate data entry, contribution processing, reconciliation, and ongoing record maintenance.

For HR teams, getting UAN management right from the beginning can prevent many complications later—for both the employee and the organization.

Note: EPFO processes, authentication requirements, and portal procedures can be updated. Employers should verify the latest EPFO requirements before processing UAN/PF matters.

Level Up HR Solutions 📞 +91 8714805999 📧 info@leveluphrs.com 🌐 www.leveluphrs.com

#PF #UAN #EPF #PFCompliance #UANManagement #PayrollCompliance #HRCompliance #EPFO #HRIndia #PayrollManagement #StatutoryCompliance #EmployeeOnboarding #KeralaBusiness #KochiBusiness #LevelUpHRSolutions

15Sep

ESI Wage Components Explained: What Is Included and What Is Excluded?

by Naziha , Digital Marketing Executive

For many HR and payroll professionals, calculating Employee State Insurance (ESI) contributions can become confusing when an employee’s salary includes multiple components.

Basic salary, Dearness Allowance (DA), House Rent Allowance (HRA), overtime, bonuses, incentives, reimbursements, and other allowances may all appear on a salary slip. But an important question remains:

Which of these components are actually considered “wages” for ESI contribution purposes?

Getting this wrong can create payroll discrepancies and compliance risks. Incorrectly excluding a wage component may result in a contribution shortfall, while including an amount that should not be treated as ESI wages can lead to unnecessary deductions.

For employers, the key is to understand that ESI wages are not always the same as gross salary or take-home salary.

This guide explains the major ESI wage components, what is generally included, what is generally excluded, and the common mistakes HR teams should avoid.


What Are ESI Wages?

Under the Employees’ State Insurance framework, “wages” are broadly defined and include remuneration paid or payable to an employee under the terms of the employment contract.

The definition also includes certain additional payments, while specifically excluding some categories of payments.

For practical payroll purposes, HR teams need to review each salary component instead of simply assuming that every item shown on a payslip is treated in the same way.


ESI Contribution Rates: A Quick Overview

ESI contributions are generally calculated as a percentage of applicable wages.

At present, the commonly applicable contribution rates are:

  • Employee contribution: 0.75%

  • Employer contribution: 3.25%

This means the contribution is calculated on eligible ESI wages, subject to the applicable coverage and wage rules.

For example, if an employee’s applicable ESI wages for a month are ₹20,000:

  • Employee contribution at 0.75% = ₹150

  • Employer contribution at 3.25% = ₹650

The total contribution would be ₹800.

However, before performing the calculation, the employer must first determine which salary components form part of ESI wages.


What Is Generally Included in ESI Wages?

1. Basic Salary

Basic salary is generally included in ESI wages.

This is the fixed core component of an employee’s salary and is normally one of the primary components used for ESI contribution calculations.

Example

  • Basic Salary: ₹15,000

This amount would generally be considered for ESI wage calculations.


2. Dearness Allowance (DA)

Dearness Allowance (DA) is generally included in ESI wages.

DA is paid to employees to help address changes in the cost of living and forms part of the remuneration received under employment.

Example

  • Basic Salary: ₹15,000

  • DA: ₹3,000

The amount considered for ESI wage calculations would generally include both components, subject to the overall wage definition and applicable rules.


3. House Rent Allowance (HRA)

HRA is generally included in ESI wages when it is paid as part of the employee’s regular remuneration.

This is one area where HR professionals sometimes make incorrect assumptions because HRA is treated differently under different statutory frameworks.

For ESI purposes, the salary component should be examined based on the applicable definition of wages rather than automatically applying PF rules to ESI calculations.


4. Regular Allowances

Regular allowances paid as part of the employee’s remuneration may generally form part of ESI wages.

Examples may include:

  • Special allowance

  • City compensatory allowance

  • Other regular cash allowances

The exact treatment can depend on the nature and conditions of the payment.

A useful question for payroll teams is:

Is this amount paid regularly as part of the employee’s remuneration for employment?

If yes, it may need to be considered under the ESI wage definition.


5. Incentive Payments

Regular incentive payments may require careful examination.

If an incentive is paid as part of the employment arrangement, HR teams should review whether it falls within the definition of wages for ESI purposes.

Instead of automatically including or excluding incentives based only on their name, organizations should examine:

  • How frequently the payment is made

  • Whether it is part of the employment contract

  • Whether it is linked to regular work

  • The nature of the payment


What Is Generally Excluded From ESI Wages?

The ESI Act specifically excludes certain categories from the definition of wages.

1. Employer’s Contribution to PF or Pension Funds

Amounts paid by the employer as contributions to:

  • Provident Fund

  • Pension Fund

are generally excluded from ESI wages.

These contributions are employer benefits and are not treated as direct wages paid to the employee.


2. Travelling Allowance and Travel Expenses

Amounts paid to cover:

  • Travel expenses

  • Travelling allowances

  • Expenses incurred because of employment-related travel

are generally excluded when they represent genuine reimbursement or expenses related to employment.

However, HR teams should distinguish between actual expense reimbursement and a fixed allowance that may form part of regular remuneration.


3. Payments Made to Cover Special Employment Expenses

Payments made specifically to compensate an employee for expenses that arise because of the nature of employment may generally be excluded.

For example, a genuine reimbursement for expenses incurred while performing work duties may not be treated in the same way as a regular salary allowance.

Proper documentation is important.


4. Gratuity Payments

Gratuity payments are generally excluded from ESI wages.

Gratuity is a statutory or employment-related terminal benefit rather than regular monthly remuneration.


5. Payments Made During Certain Periods of Absence

The treatment of payments related to periods when an employee is not working requires careful consideration.

The ESI definition specifically addresses certain payments connected with periods of absence from work, including leave, lay-off, strike, or lockout, where the employee is not entitled to remuneration.

HR teams should review the exact circumstances and applicable rules before calculating contributions.


What About Overtime?

Overtime is a commonly misunderstood component.

Overtime wages are generally excluded from ESI contribution calculations.

However, overtime payments may still be relevant when considering other aspects of payroll or statutory compliance.

This is why employers should avoid applying one payroll rule to every compliance requirement.


What About Bonuses?

The treatment of bonuses depends on the type and nature of the payment.

Certain types of bonuses may be treated differently from regular wages.

For example, statutory or annual bonus payments may not always be handled in the same way as regular monthly remuneration.

HR teams should carefully review the nature of the bonus before deciding whether ESI contributions apply.


A Simple Example of ESI Wage Calculation

Consider the following salary structure:

Salary ComponentAmountGeneral ESI TreatmentBasic Salary₹15,000IncludedDearness Allowance₹2,000IncludedHRA₹5,000Generally includedSpecial Allowance₹3,000Depends on nature; often requires reviewOvertime₹1,500Generally excludedTravel Reimbursement₹1,000Generally excluded if genuine reimbursementTotal Gross Amount₹27,500Not automatically equal to ESI wages

The employer should determine the applicable ESI wage base by examining each component according to the statutory definition of wages.

This is why gross salary should not automatically be used as the ESI contribution base without reviewing the salary structure.


Common Mistakes HR Teams Make When Calculating ESI

1. Using Gross Salary Without Reviewing Components

A common mistake is calculating ESI on the entire gross salary without examining individual salary components.

Some items may be excluded, while others must be included.


2. Assuming PF Rules Apply to ESI

PF and ESI have different definitions and treatment of wage components.

A component excluded from PF calculations is not automatically excluded from ESI.


3. Incorrectly Excluding HRA

Some payroll teams automatically exclude HRA because of its treatment under other payroll or tax frameworks.

However, ESI calculations follow their own wage definition.


4. Treating Every Reimbursement as an Exclusion

A genuine reimbursement may be excluded, but organizations should maintain proper supporting documentation.

Simply naming a regular payment as a “reimbursement” does not automatically determine its treatment.


5. Ignoring Changes in Salary Structure

Promotions, salary revisions, and new allowances can change the composition of an employee’s remuneration.

HR teams should review ESI calculations whenever salary structures change.


The Importance of the ₹21,000 Wage Limit

For most employees, the ESI coverage wage limit is commonly ₹21,000 per month, subject to applicable provisions and exceptions.

Employees with wages within the prescribed limit may fall under ESI coverage if the establishment and employee meet the applicable eligibility requirements.

However, HR teams should remember that coverage and contribution obligations can be affected by factors such as:

  • The applicable contribution period

  • Wage changes during a contribution period

  • Existing employee coverage status

  • Applicable exemptions or special provisions

For this reason, employers should not automatically stop ESI contributions simply because an employee receives an increment that increases wages beyond the limit during an applicable contribution period.


A Simple ESI Compliance Checklist

Before finalizing monthly payroll, HR teams should check:

✔ Is the employee covered under the applicable ESI provisions?

✔ Have eligible wage components been correctly identified?

✔ Have excluded payments been properly documented?

✔ Are overtime payments handled correctly?

✔ Are reimbursements supported by relevant records?

✔ Have salary structure changes been reviewed?

✔ Are employee and employer contributions calculated correctly?

✔ Are contributions deposited within the required timeline?


How Payroll Software Can Help

Modern payroll software can simplify ESI compliance by helping organizations:

  • Maintain employee salary structures

  • Automatically calculate contributions

  • Track eligibility

  • Manage contribution records

  • Generate payroll reports

  • Reduce manual calculation errors

However, HR teams should periodically review software settings.

If a salary component is incorrectly configured, automation can repeat the same mistake every month.


Final Thoughts

Understanding ESI wage components is essential for accurate payroll and statutory compliance.

The most important point to remember is that ESI wages are not necessarily the same as an employee’s gross salary. Each payment component should be reviewed based on its nature and the applicable definition of wages.

Basic salary and DA generally form part of ESI wages, while certain items such as employer contributions to PF, genuine travel-related expenses, and gratuity are generally excluded. Other components, including allowances, incentives, and bonuses, may require a closer review depending on how they are structured and paid.

For HR and payroll teams, the safest approach is to maintain clear salary structures, document reimbursements properly, review changes regularly, and stay updated with official ESI requirements.

When there is uncertainty about a particular salary component, it is always better to verify the latest ESIC guidance or seek professional compliance advice before making a contribution decision.

Accurate ESI calculations not only help organizations avoid compliance issues—they also ensure that employees receive the social security protection they are entitled to.

11Sep

Employee Resignation Documentation: What Should Be Recorded from Resignation to Relieving?

By Nandana G.S , Digital Marketing Executive

Employee resignation is not just the end of an employment relationship. From an HR perspective, it is a documentation and compliance process that should be handled carefully from the moment an employee submits resignation until the final relieving and settlement.

Proper resignation documentation helps businesses maintain accurate employee records, avoid misunderstandings, and provide evidence of decisions taken during the exit process.

1. Resignation Letter or Email

The process should begin with a clear record of the employee’s resignation.

HR should maintain:

  • Date of resignation

  • Employee’s name and designation

  • Resignation communication

  • Reason for resignation, if voluntarily provided

  • Proposed last working day

  • Notice period details

The original resignation email or letter should be preserved as part of the employee’s exit records.

2. Resignation Acknowledgement

HR should formally acknowledge the resignation and communicate the next steps to the employee.

The acknowledgement may include:

✔️ Acceptance of resignation ✔️ Notice period requirements ✔️ Proposed last working day ✔️ Handover expectations ✔️ Exit formalities ✔️ Company property return requirements

Clear communication at this stage can prevent confusion later.

3. Notice Period and Last Working Day

HR should maintain documentation showing how the notice period was calculated.

Any changes to the last working day should also be documented, particularly when there is:

  • Notice period waiver

  • Early release

  • Extension of notice period

  • Leave adjustment

  • Management-approved changes

Verbal agreements should not replace proper written documentation.

4. Handover Documentation

A structured handover process is essential, particularly for employees handling clients, projects, systems, finances, or critical business responsibilities.

The handover record may include:

  • Pending tasks

  • Project status

  • Client information

  • Important documents

  • System or process details

  • Responsible replacement/team member

  • Handover completion confirmation

This helps ensure business continuity after the employee leaves.

5. Exit Interview Records

An exit interview can provide valuable insights into employee experience and organizational issues.

HR may document feedback relating to:

  • Reason for leaving

  • Management experience

  • Work environment

  • Compensation and benefits

  • Career growth

  • Workload

  • Suggestions for improvement

Exit interview information should be handled appropriately and confidentially.

6. Company Assets and Access

Before relieving an employee, HR should coordinate with the relevant departments to confirm the return of company property.

This may include:

✔️ Laptop and other devices ✔️ ID cards and access cards ✔️ Documents and files ✔️ Keys ✔️ Other company assets

IT teams should also document the appropriate deactivation or modification of access to company systems, email, applications, and other business resources.

7. Leave and Attendance Records

The employee’s attendance and leave records should be reviewed before final settlement.

HR/payroll should verify:

  • Attendance up to the last working day

  • Leave balance

  • Leave encashment, where applicable

  • Unpaid leave

  • Notice-period attendance

  • Any approved adjustments

Accurate records help ensure the final payroll calculation is correct.

8. Full and Final Settlement Documentation

The Full and Final (FnF) settlement should be supported by proper calculations and records.

Depending on the employee’s circumstances, this may involve:

  • Salary payable

  • Leave encashment

  • Reimbursements

  • Incentives or variable pay, where applicable

  • Deductions

  • Advances or recoveries

  • Other applicable dues

HR and payroll teams should maintain supporting records for the settlement rather than relying only on the final payment entry.

9. Statutory and Employment Records

Employee exits may also require updates to applicable statutory and employment records.

Depending on the employee and applicable laws, HR should review relevant requirements relating to PF, ESI, TDS, gratuity, Professional Tax, and other statutory obligations.

The exact requirements can vary based on the employee’s circumstances and applicable law.

10. Relieving and Experience Documents

Once the exit process is completed, the organization should issue the appropriate employment documents according to its policies and applicable requirements.

Common documents may include:

  • Relieving letter

  • Experience/service certificate

  • Full and final settlement statement

  • Other applicable employment or statutory documents

The employee’s personnel file should also be updated to reflect the completed exit.

Common Resignation Documentation Mistakes

Many organizations create problems by:

❌ Accepting resignations without maintaining written records ❌ Failing to document changes to the last working day ❌ Relying on verbal handover confirmations ❌ Not reconciling leave and attendance ❌ Maintaining incomplete FnF calculations ❌ Delaying exit documentation ❌ Failing to update employee and statutory records ❌ Not maintaining a standardized exit checklist

A Simple Employee Exit Documentation Checklist

HR teams can use a structured checklist covering:

Resignation → Acknowledgement → Notice Period → Handover → Exit Interview → Asset Clearance → Attendance & Leave → FnF Settlement → Statutory Updates → Relieving & Experience Documents → Employee File Closure

Having a standardized process ensures that every employee exit is handled consistently.

How Level Up HR Solutions Can Help

At Level Up HR Solutions, we help businesses strengthen their HR processes through HR documentation, payroll compliance, statutory compliance, HR audits, employee record management, and HR policy support.

A properly documented employee exit protects both the organization and the employee by creating a clear record of what was communicated, completed, and settled.

Final Thoughts

Employee resignation should not be treated as simply receiving a resignation letter and issuing a relieving letter.

A well-managed exit process creates a complete, organized, and auditable trail from resignation to final settlement and relieving. For growing businesses, standardizing this process can significantly improve HR efficiency, documentation quality, and compliance readiness.

Level Up HR Solutions 📞 +91 8714805999 📧 info@leveluphrs.com 🌐 www.leveluphrs.com

#EmployeeResignation #EmployeeExitProcess #HRDocumentation #HRCompliance #PayrollCompliance #FullAndFinalSettlement #EmployeeRecords #HRIndia #StatutoryCompliance #HRManagement #KeralaBusiness #KochiBusiness #LevelUpHRSolutions