18Sep

Old vs New Tax Regime: What Employers Need to Consider While Processing Payroll

by Naziha , Digital Marketing Executive

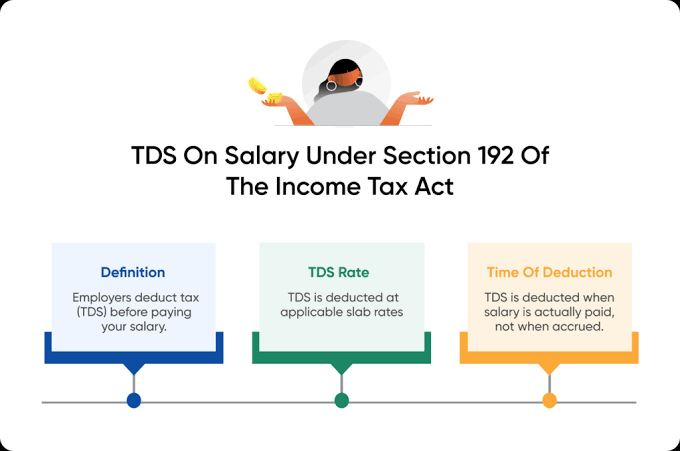
Processing employee salaries is not just about calculating gross pay and transferring the final amount to an employee’s bank account. One of the most important responsibilities for employers and payroll teams is calculating and deducting the correct amount of Tax Deducted at Source (TDS).

With employees having a choice between the old and new tax regimes, payroll processing has become more complex. HR and payroll teams must understand the employee’s tax regime, consider eligible deductions and exemptions, calculate projected annual taxable income, and ensure that monthly TDS is deducted correctly.

A wrong tax calculation can create problems for both the employer and the employee. Employees may face unexpected tax deductions or refunds, while employers may face payroll corrections and compliance issues.

For the 2026–27 tax year, payroll teams also need to ensure that their systems and processes reflect the applicable tax rules for the relevant period.

This guide explains the key differences between the old and new tax regimes and what employers should consider while processing employee payroll.


Understanding the Old and New Tax Regimes

India currently provides different tax structures for eligible individual taxpayers.

The new tax regime is the default regime, while eligible taxpayers can choose to opt for the old regime. The two regimes differ mainly in their tax rates and the availability of deductions and exemptions.

The old regime generally provides access to a wider range of deductions and exemptions, while the new regime generally offers different tax slabs and allows only limited deductions and exemptions.

For employers, this means payroll processing cannot follow a one-size-fits-all approach.


What Is the Old Tax Regime?

The old tax regime follows the traditional tax structure.

Under this regime, employees may be able to claim various eligible tax deductions and exemptions, subject to applicable conditions and limits.

Common examples may include:

  • House Rent Allowance (HRA), subject to applicable conditions

  • Leave Travel Allowance (LTA), where eligible

  • Certain deductions relating to investments

  • Eligible insurance-related deductions

  • Eligible deductions for specified expenses

  • Home loan-related tax benefits, where applicable

Because more deductions and exemptions may be available, the old regime can be beneficial for some employees who have significant eligible tax-saving investments or exemptions.

However, payroll teams must collect and verify the required declarations and supporting documents where necessary.


What Is the New Tax Regime?

The new tax regime is the default tax regime for eligible taxpayers.

It generally provides a different tax slab structure while allowing fewer deductions and exemptions compared with the old regime.

Under the official slab information available for AY 2026–27, the new regime for most individual taxpayers uses the following slab structure:

Taxable IncomeTax RateUp to ₹4 lakhNil₹4 lakh – ₹8 lakh5%₹8 lakh – ₹12 lakh10%₹12 lakh – ₹16 lakh15%₹16 lakh – ₹20 lakh20%₹20 lakh – ₹24 lakh25%Above ₹24 lakh30%

These rates are subject to applicable provisions, rebate rules, surcharge, and Health and Education Cess.

The lower or differently structured tax rates may benefit employees who do not have substantial deductions or exemptions available under the old regime.


Old Tax Regime vs New Tax Regime: A Quick Comparison

FactorOld Tax RegimeNew Tax RegimeDefault regimeNoYesTax slabsTraditional slab structureRevised slab structureDeductionsMore deductions may be availableLimited deductionsExemptionsSeveral exemptions may be availableMany exemptions are restrictedInvestment declarationsOften important for tax calculationDepends on eligible deductionsBest optionDepends on employee’s deductions and exemptionsDepends on employee’s income and tax position

There is no single regime that is automatically best for every employee.

The better option depends on factors such as:

  • Annual income

  • Eligible deductions

  • Eligible exemptions

  • Investments

  • Salary structure

  • Other taxable income

The Income Tax Department itself advises taxpayers to compare the tax liability under both regimes before making a decision.


1. Collect the Employee’s Tax Regime Intimation

One of the first things employers should do is obtain the employee’s intended tax regime for payroll purposes.

According to Income Tax Department guidance, an employee should intimate the employer regarding their intended tax regime during the year. If the employee does not provide an intimation, the employer generally treats the employee under the default new tax regime for TDS purposes.

Best practice for employers

At the beginning of the financial year, provide employees with a clear process to:

  • Select their intended tax regime for payroll purposes

  • Submit required declarations

  • Provide relevant information for TDS calculations

This helps payroll teams avoid incorrect assumptions.


2. Do Not Treat Every Employee the Same

A common payroll mistake is assuming that all employees should be processed under the same tax regime.

Employees have different financial situations.

For example:

Employee A

May have:

  • Significant eligible investments

  • Eligible HRA exemptions

  • Other applicable deductions

The old regime may potentially be more favourable.

Employee B

May have:

  • Few tax-saving investments

  • Limited exemptions

  • A relatively simple salary structure

The new regime may potentially result in a better tax outcome.

Employers should not recommend a regime without considering the individual’s circumstances. Their primary responsibility is to process payroll correctly based on the applicable rules and employee declarations.


3. Understand the Impact on Investment Proof Collection

The old and new regimes can significantly affect how HR teams collect investment declarations and proofs.

Under the old tax regime, employee declarations and eligible supporting documents may be important for calculating deductions and exemptions.

Payroll teams may need to process information relating to eligible:

  • Investments

  • Insurance payments

  • Rent details

  • Other deductions

  • Applicable exemptions

Under the new regime, many traditional deductions and exemptions are not available, although certain specified benefits may still be permitted under applicable tax provisions.

This can reduce the number of investment proofs required for some employees.

However, employers should not assume that no declarations are ever required under the new regime. The payroll team must consider deductions or exemptions that remain available under the applicable rules.


4. Calculate TDS Based on Projected Annual Income

Salary TDS should not simply be calculated by applying a tax percentage to one month’s salary.

Employers generally need to estimate the employee’s projected taxable income for the relevant tax year.

The calculation may include:

  • Monthly salary

  • Bonus payments

  • Incentives

  • Arrears

  • Other taxable benefits

  • Eligible exemptions

  • Applicable deductions

Once projected taxable income is determined, the employer can calculate the estimated annual tax liability and distribute the TDS appropriately across the remaining payroll months.

This is particularly important when an employee receives:

  • A salary increment

  • A bonus

  • A promotion

  • Variable pay

  • Additional taxable benefits


5. Update TDS When Salary Changes

Employee tax calculations should not remain unchanged throughout the year if the employee’s income changes.

For example, an employee may receive:

  • A salary increase

  • Annual bonus

  • Performance incentive

  • Sales commission

  • Arrears

These changes can increase projected annual income and affect the employee’s tax liability.

Payroll teams should review TDS calculations periodically rather than waiting until the end of the financial year.


6. Handle New Joiners Carefully

When a new employee joins an organization during the financial year, their current employer may need information about salary received from previous employment.

Without considering previous salary income, the employer may calculate TDS only on the salary paid by the current organization, potentially resulting in incorrect overall tax deductions.

HR and payroll teams should have a structured process for collecting relevant previous employment and salary information where required for accurate TDS processing.


7. Keep Accurate Employee Declarations and Records

Payroll compliance depends heavily on documentation.

Employers should maintain appropriate records relating to:

  • Employee tax regime intimation

  • Salary declarations

  • Investment declarations

  • Supporting documents, where applicable

  • Previous employment income information

  • Tax calculations

  • TDS deductions

Proper documentation can help organizations explain and support payroll calculations if questions arise later.


8. Understand That the New Regime Is the Default for Payroll Purposes

The new tax regime is the default regime under the applicable framework.

If an employee does not intimate their intended choice to the employer for the relevant year, the employer generally deducts TDS based on the default new tax regime.

This makes employee communication extremely important.

A simple annual email or HR portal declaration can help reduce confusion.


9. Employees May Have Different Options at the Return Stage

Employers should understand the difference between:

  • TDS processing during the year, and

  • The employee’s final tax position when filing their income tax return

For eligible individuals without business or professional income, the option relating to the tax regime may generally be exercised according to the applicable rules when filing the income tax return.

The employer’s payroll calculation is based on the information and regime intimation provided for TDS purposes during the year.

This is why employees should understand that payroll TDS and final tax return filing are related but should not always be treated as identical processes.


10. Update Payroll Systems for Current Tax Rules

Tax rules and administrative provisions can change.

For 2026–27, the Income Tax Department has specifically advised employers to reset TDS computation from 1 April 2026 for the new tax year, considering projected income, deductions, and the applicable tax regime. Payroll systems also need to reflect the relevant legislative and section-numbering changes applicable to the new tax year.

Payroll teams should ensure that:

  • Tax slabs are updated

  • TDS formulas are reviewed

  • The correct tax year is selected

  • Regime options are configured properly

  • Payroll software reflects current requirements

Using outdated payroll settings can result in incorrect deductions for every employee.


Common Payroll Mistakes Employers Should Avoid

1. Automatically Applying the Same Regime to Everyone

Employees may have different tax situations.

Always obtain the required regime intimation and process TDS accordingly.


2. Using Outdated Tax Slabs

Tax slabs can change from one tax year to another.

Payroll software should be reviewed at the beginning of every financial year.


3. Ignoring Employee Investment Declarations

For employees using the old regime, eligible declarations and supporting information can significantly affect taxable income.


4. Forgetting Salary Revisions

A salary increment or bonus can change projected annual tax liability.

TDS should be recalculated when necessary.


5. Not Considering Previous Employment Income

New employees may already have received taxable salary from another employer during the same year.


6. Waiting Until the Last Month to Correct TDS

Waiting until the end of the year can result in a large and unexpected TDS deduction from the employee’s final salaries.

Periodic reviews are much better.


A Simple Payroll Checklist for HR Teams

Before finalizing payroll, HR and payroll teams should check:

✔ Has the employee provided their tax regime intimation?

✔ Is the default regime being applied correctly where no intimation has been provided?

✔ Are the current tax slabs configured correctly?

✔ Has projected annual income been calculated?

✔ Have salary increments and bonuses been considered?

✔ Are applicable deductions and exemptions processed correctly?

✔ Have required declarations and documents been collected?

✔ Has previous employment income been considered where necessary?

✔ Has monthly TDS been reviewed and adjusted?

✔ Are payroll records securely maintained?


How Technology Can Simplify Tax Regime Management

Modern payroll systems can help employers manage tax compliance by:

  • Allowing employees to select a tax regime

  • Collecting declarations digitally

  • Tracking investment submissions

  • Calculating projected tax liability

  • Automatically adjusting TDS

  • Generating payroll reports

  • Maintaining employee records

However, automation should always be supported by regular payroll reviews.

Incorrect system configuration can automate errors just as efficiently as it automates correct calculations.


Final Thoughts

The choice between the old and new tax regimes has made payroll processing more important than simply calculating monthly salary.

Employers need a structured process to collect employee tax regime information, calculate projected annual income, process eligible deductions and exemptions, and review TDS regularly throughout the year.

The new tax regime is the default, but the most suitable regime can vary depending on an employee’s income, deductions, and exemptions.

For HR and payroll teams, the goal is not to decide which tax regime is universally better. The goal is to ensure that payroll calculations are accurate, employee declarations are properly recorded, and TDS is processed according to the latest applicable rules.

By maintaining updated payroll systems, communicating clearly with employees, and reviewing TDS throughout the year, employers can reduce errors and make tax compliance significantly easier.

When tax rules or an employee’s circumstances are complex, organizations should verify the latest official guidance or seek advice from a qualified tax professional before making payroll decisions.
17Sep

Employee Joins or Leaves Mid-Month: How Does Professional Tax Deduction Work?

Introduction

Professional Tax is a statutory deduction that often creates confusion for HR and payroll teams, especially when an employee joins or leaves an organisation in the middle of a month.

Unlike income tax, Professional Tax is a state-level tax. The applicable rate, salary threshold, payment frequency, exemptions, and calculation method depend on the state in which the employee is working. Therefore, there is no single nationwide formula that can be applied to every employee.

One of the most common payroll questions is:

“If an employee works only part of a month, should Professional Tax still be deducted?”

The answer depends on the applicable state’s Professional Tax legislation and the specific rules used to determine liability.

For HR teams, this becomes particularly important during employee onboarding, full-and-final settlement, payroll processing, transfers, and monthly statutory compliance.

In this guide, we will explain how Professional Tax generally works when an employee joins or leaves mid-month, what payroll teams should check, common mistakes to avoid, and how organisations can make PT processing more accurate.


What Is Professional Tax?

Professional Tax is a tax imposed by state governments on individuals engaged in professions, trades, callings, or employment.

For salaried employees, the employer generally deducts the applicable Professional Tax from salary and deposits it with the relevant state authority or local body.

The tax is not the same as income-tax TDS.

Professional Tax is:

  • State-specific

  • Governed by applicable state legislation

  • Usually linked to salary or income slabs

  • Deducted by employers from eligible employees

  • Subject to state-specific exemptions and rules

For example, Karnataka’s official Professional Tax portal states that employers are responsible for deducting and paying Professional Tax for eligible employees according to the applicable slab.


Why Mid-Month Joining Creates Confusion

Suppose an employee joins a company on the 15th of the month.

They don’t receive their full monthly salary because they have worked only part of the month.

For example:

Monthly salary: ₹40,000

Days worked: 15

Salary paid for the month: approximately ₹20,000

The question then becomes:

Should Professional Tax be calculated on ₹40,000 or ₹20,000?

There is no universal answer.

The payroll team must check the Professional Tax rules applicable in the relevant state, including how the salary slab and liability are determined.

This is why HR teams should not automatically apply a standard “pro-rata PT” rule to every employee.


Professional Tax Is State-Specific

This is the first rule HR teams should remember.

Professional Tax is not administered through one uniform national slab.

Different states can have different:

  • Salary thresholds

  • Tax slabs

  • Deduction amounts

  • Payment frequencies

  • Exemptions

  • Registration requirements

  • Calculation methods

For example, Karnataka currently provides a monthly exemption threshold for salaried employees below the prescribed salary limit, with the applicable slab determined under Karnataka’s Professional Tax rules.

Kerala follows a different framework, with profession tax administered through the applicable local-body/state system and collected from eligible employees.

Therefore, HR teams should always begin with:

Which state and local authority’s Professional Tax rules apply to this employee?


When an Employee Joins Mid-Month

Consider an employee who joins on 16 August.

Their monthly salary is ₹35,000, but because they joined in the middle of the month, they receive only a proportionate salary for August.

The payroll team should determine:

  1. The employee’s applicable work location.

  2. Whether the employee is liable for Professional Tax.

  3. Which salary amount is relevant under the applicable state rules.

  4. Whether the state uses monthly, half-yearly, or another assessment/payment mechanism.

  5. Whether any exemption applies.

  6. Whether the employee’s employment duration affects liability.

Only after checking these factors should the payroll team calculate the deduction.


Does Joining Mid-Month Automatically Mean No Professional Tax?

No.

A common payroll misconception is that an employee who works only part of a month is automatically exempt from Professional Tax.

That is not necessarily correct.

Some states or local authorities may determine liability based on the applicable salary/income slab and prescribed rules, while others may have different assessment or collection mechanisms.

Therefore:

Mid-month joining ≠ automatic PT exemption.

The applicable state legislation should determine the treatment.


Example: Mid-Month Joiner

Imagine an employee has:

Monthly salary: ₹50,000

Joining date: 20 August

Because the employee worked only part of August, their actual salary payment for August may be substantially lower than their full monthly salary.

The payroll team should not simply assume:

“Salary is below the PT threshold this month, so PT is zero.”

Instead, payroll should check the applicable state’s rules to determine whether the threshold is based on the actual salary paid for that period or another prescribed basis.

This distinction can prevent incorrect deductions.


When an Employee Leaves Mid-Month

The same issue occurs when an employee resigns or is terminated during the month.

Suppose an employee leaves on 12 September.

Their normal monthly salary is ₹45,000, but their final month’s salary is calculated only for the days worked.

The payroll team must determine the applicable Professional Tax treatment before processing the employee’s final salary.

This is particularly important because the final payroll may include:

  • Salary for days worked

  • Leave encashment

  • Overtime

  • Incentives

  • Other eligible payments

  • Deductions

  • Full-and-final settlement amounts

The treatment of each component may depend on the applicable rules.


Professional Tax During Full and Final Settlement

Full-and-final settlement is an important area for HR teams.

When an employee leaves, payroll should review all statutory deductions before releasing the final settlement.

The organisation should verify:

  • Outstanding Professional Tax

  • Applicable PT for the relevant period

  • Salary payable

  • Leave-related payments

  • Other statutory deductions

  • Final payroll records

Kerala’s profession-tax rules, for example, specifically provide for recovery of profession tax in certain employee-relieving situations, demonstrating why exit payroll should be checked against the applicable local rules rather than handled using a generic formula.


Monthly vs Half-Yearly Professional Tax

Another important factor is the frequency with which Professional Tax is assessed or collected.

Not every state follows exactly the same mechanism.

For example, the official Kerala Professional Tax portal states that profession tax is paid on a semi-annual basis under the applicable system.

In contrast, Karnataka operates a monthly deduction/payment structure for employee Professional Tax.

This difference can significantly affect how HR teams handle employees who join or leave during a particular month.

Therefore, payroll teams should not assume that a monthly calculation method applies across all states.


What If an Employee Works in One State but Is Paid From Another?

This situation is common for companies with headquarters in one state and branches in several others.

For Professional Tax purposes, the employee’s place of work can be important.

For example, Karnataka’s official Professional Tax FAQ states that where a company is registered in another state but employees work in Karnataka, the Professional Tax is payable in the state where the employees are working, irrespective of where salary is disbursed.

Therefore, payroll teams should maintain accurate employee work-location information.


What HR Teams Should Check for Mid-Month Joiners

Before processing PT for a new employee, HR/payroll teams should verify:

1. Employee Work Location

Identify the state and relevant local authority.

2. Salary Details

Check the applicable salary or wage information.

3. PT Registration

Confirm that the employer has the required Professional Tax registration where applicable.

4. State Slab

Review the current applicable Professional Tax slab.

5. Exemptions

Check whether the employee falls under any prescribed exemption.

6. Joining Date

Record the exact date the employee started work.

7. Payroll Amount

Check the salary actually payable for the relevant period.

8. Assessment Method

Determine whether the applicable state uses monthly, half-yearly, or another prescribed method.


What HR Teams Should Check for Employees Leaving Mid-Month

For an employee leaving during the month, payroll should verify:

  • Last working date

  • Salary payable for the month

  • Applicable PT liability

  • Previous PT deductions

  • Outstanding statutory deductions

  • Full-and-final settlement

  • Required statutory records

  • PT payment and reporting requirements

A final payroll checklist can prevent missed deductions or incorrect recovery.


Common Professional Tax Mistakes

1. Applying One State’s Rule Everywhere

A company operating across India may have employees subject to different PT rules.

Using one generic slab can create errors.

2. Automatically Pro-Rating PT

Not every state follows the same pro-rata calculation method.

3. Ignoring Work Location

Professional Tax is linked to state-level rules, so employee work location matters.

4. Missing State-Specific Exemptions

Some states provide exemptions for specific categories of employees.

5. Using Outdated Slabs

PT slabs and requirements can change through state notifications.

6. Incorrect Full-and-Final Processing

The final month should be reviewed carefully before releasing settlement.


How Payroll Software Can Help

Professional Tax calculations can become complicated when an organisation has employees across multiple states.

Payroll software can help HR teams manage:

  • Employee work locations

  • State-specific PT rules

  • Salary calculations

  • Mid-month joining

  • Mid-month exits

  • Statutory deductions

  • Payroll reports

  • Full-and-final settlement

  • Compliance records

Automation can reduce repetitive calculations and minimise manual errors.

However, payroll software must be configured with the correct and current state-specific rules.

Technology can automate a calculation, but it cannot compensate for an incorrect statutory configuration.


A Simple Payroll Workflow

HR teams can follow this process for every employee:

Step 1: Identify the employee’s work state.

Step 2: Confirm whether Professional Tax applies.

Step 3: Check the current state-specific slab and exemptions.

Step 4: Review the employee’s joining or leaving date.

Step 5: Determine the salary applicable for the relevant period.

Step 6: Apply the prescribed calculation method.

Step 7: Deduct PT through payroll where applicable.

Step 8: Record and remit the deduction according to the required timeline.

Step 9: Review the payroll before final submission.

This process creates consistency and reduces the risk of missed statutory deductions.


Professional Tax Compliance Checklist

For HR and payroll teams:

✓ Confirm the employee’s work location

✓ Identify the applicable state PT law

✓ Check the current salary slab

✓ Verify applicable exemptions

✓ Check joining/exit date

✓ Determine the applicable assessment method

✓ Calculate PT according to state rules

✓ Deduct the correct amount

✓ Maintain payroll records

✓ Remit PT within the prescribed timeline

✓ Complete required returns or filings

✓ Review full-and-final settlements


Conclusion

Professional Tax deduction becomes particularly important when an employee joins or leaves in the middle of a month. While it may appear to be a simple payroll deduction, the actual treatment can depend on state-specific legislation, salary slabs, exemptions, assessment periods, work location, and the employee’s employment dates.

The most important point for HR teams is that there is no single Professional Tax rule that applies uniformly across India. Each state that levies Professional Tax can prescribe its own framework. Kerala, Karnataka, Maharashtra, and other states may therefore require different payroll approaches.

HR teams should avoid automatically pro-rating or waiving Professional Tax simply because an employee worked only part of a month. Instead, payroll should check the applicable state rules, determine the correct basis of liability, and ensure that deductions and statutory payments are accurately recorded.

For organisations with employees across multiple locations, a state-wise Professional Tax matrix combined with reliable payroll software can make compliance significantly easier.

Ultimately, accurate Professional Tax processing is about more than getting one payroll deduction right. It is about maintaining a consistent, transparent, and compliant payroll system that protects both the organisation and its employees.

Important note: Professional Tax rules, slabs, exemptions, assessment periods, and procedures vary by state and may change through government notifications. HR teams should verify the latest applicable

state rules before processing payroll. 

16Sep

PF UAN Management: What HR Teams Need to Do for New Employees

By Nandana G.S , Digital Marketing Executive

When a new employee joins an organization, PF compliance should begin from the onboarding stage itself. One of the most important parts of this process is ensuring that the employee’s Universal Account Number (UAN) is correctly identified, linked, and maintained.

A UAN provides a unified identity for an employee’s EPF accounts across different employments. For HR and payroll teams, proper UAN management helps avoid duplicate accounts, incorrect member details, and unnecessary compliance issues.

1. Check Whether the Employee Already Has a UAN

Before creating or processing a new PF account, HR should determine whether the employee already has a UAN from previous employment.

The employee may have an existing UAN even if they have changed:

  • Employer

  • Job role

  • Location

  • Industry

  • Organization

HR should avoid creating duplicate UANs unnecessarily.

2. Collect Accurate Employee Information

During onboarding, HR should collect and verify the information required for PF-related processing.

Important details may include:

✔️ Employee name ✔️ Date of birth ✔️ Aadhaar details as applicable ✔️ Bank account information ✔️ Mobile number ✔️ Existing UAN, if available ✔️ Previous employment details, where relevant

The information submitted for PF records should match the employee’s supporting records.

3. Verify UAN and KYC Details

HR/payroll teams should ensure that the employee’s UAN-related information and KYC records are properly maintained.

Depending on the applicable EPFO process, this may involve verification of:

  • Aadhaar

  • Bank account

  • PAN, where applicable

  • Mobile number

  • Name and date-of-birth details

Incorrect information can create difficulties when employees later try to access or transfer their PF benefits.

4. Link the Employee Correctly With the New Employer

For an employee who already has a UAN, the new employment should be associated with the existing UAN rather than unnecessarily creating another identity.

HR should carefully verify the employee’s existing UAN and ensure the correct PF member/employment details are processed.

5. Handle New Employees Without an Existing UAN

If an eligible employee does not have a UAN, HR/payroll should follow the applicable EPFO process for UAN generation/allocation.

The process and authentication requirements may change over time, so HR teams should follow the latest EPFO instructions and employer portal procedures.

6. Ensure Correct PF Wage and Contribution Processing

UAN management is only one part of PF compliance.

Payroll teams should also ensure that:

✔️ PF wages are correctly determined ✔️ Employee contributions are accurately calculated ✔️ Employer contributions are correctly processed ✔️ Monthly ECR information is accurate ✔️ Contributions are remitted within the applicable timelines ✔️ Employee records are reconciled with payroll

A correct UAN does not compensate for incorrect PF calculations or payroll data.

7. Avoid Duplicate or Incorrect Employee Records

One of the common HR challenges is inconsistent information across employee records.

For example, differences in an employee’s name, date of birth, Aadhaar details, or other identifying information can cause problems with PF-related services.

HR should establish a verification step during onboarding rather than waiting until the employee faces an issue.

8. Maintain Proper Documentation

HR should maintain an organized record of PF/UAN onboarding information.

A practical checklist can include:

Employee Joining → PF Eligibility Check → Existing UAN Verification → Employee Details Verification → KYC Review → Employer/Member Record Setup → Payroll Mapping → ECR/Reconciliation → Record Maintenance

This creates a structured process for every new employee.

Common PF UAN Management Mistakes

HR teams should watch out for:

❌ Creating duplicate UANs ❌ Entering incorrect employee details ❌ Failing to verify an existing UAN ❌ Incomplete KYC information ❌ Incorrect PF wage mapping ❌ Payroll and PF records not matching ❌ Delayed correction of employee information ❌ Lack of onboarding documentation

Why UAN Management Matters for Employees

Proper UAN management makes it easier for employees to manage their PF-related records across different employments.

For employers, accurate UAN and PF records support better payroll administration, statutory compliance, reconciliation, and audit readiness.

How Level Up HR Solutions Can Help

At Level Up HR Solutions, we help businesses manage their HR and payroll processes with greater accuracy through payroll compliance, PF/ESI compliance support, HR documentation, statutory compliance reviews, and HR audits.

A strong PF onboarding process helps businesses reduce avoidable errors and ensures employee records remain organized from the beginning of employment.

Final Thoughts

PF UAN management should not be treated as a one-time onboarding formality. It should be part of a standardized HR and payroll process that includes verification, accurate data entry, contribution processing, reconciliation, and ongoing record maintenance.

For HR teams, getting UAN management right from the beginning can prevent many complications later—for both the employee and the organization.

Note: EPFO processes, authentication requirements, and portal procedures can be updated. Employers should verify the latest EPFO requirements before processing UAN/PF matters.

Level Up HR Solutions 📞 +91 8714805999 📧 info@leveluphrs.com 🌐 www.leveluphrs.com

#PF #UAN #EPF #PFCompliance #UANManagement #PayrollCompliance #HRCompliance #EPFO #HRIndia #PayrollManagement #StatutoryCompliance #EmployeeOnboarding #KeralaBusiness #KochiBusiness #LevelUpHRSolutions

15Sep

ESI Wage Components Explained: What Is Included and What Is Excluded?

by Naziha , Digital Marketing Executive

For many HR and payroll professionals, calculating Employee State Insurance (ESI) contributions can become confusing when an employee’s salary includes multiple components.

Basic salary, Dearness Allowance (DA), House Rent Allowance (HRA), overtime, bonuses, incentives, reimbursements, and other allowances may all appear on a salary slip. But an important question remains:

Which of these components are actually considered “wages” for ESI contribution purposes?

Getting this wrong can create payroll discrepancies and compliance risks. Incorrectly excluding a wage component may result in a contribution shortfall, while including an amount that should not be treated as ESI wages can lead to unnecessary deductions.

For employers, the key is to understand that ESI wages are not always the same as gross salary or take-home salary.

This guide explains the major ESI wage components, what is generally included, what is generally excluded, and the common mistakes HR teams should avoid.


What Are ESI Wages?

Under the Employees’ State Insurance framework, “wages” are broadly defined and include remuneration paid or payable to an employee under the terms of the employment contract.

The definition also includes certain additional payments, while specifically excluding some categories of payments.

For practical payroll purposes, HR teams need to review each salary component instead of simply assuming that every item shown on a payslip is treated in the same way.


ESI Contribution Rates: A Quick Overview

ESI contributions are generally calculated as a percentage of applicable wages.

At present, the commonly applicable contribution rates are:

  • Employee contribution: 0.75%

  • Employer contribution: 3.25%

This means the contribution is calculated on eligible ESI wages, subject to the applicable coverage and wage rules.

For example, if an employee’s applicable ESI wages for a month are ₹20,000:

  • Employee contribution at 0.75% = ₹150

  • Employer contribution at 3.25% = ₹650

The total contribution would be ₹800.

However, before performing the calculation, the employer must first determine which salary components form part of ESI wages.


What Is Generally Included in ESI Wages?

1. Basic Salary

Basic salary is generally included in ESI wages.

This is the fixed core component of an employee’s salary and is normally one of the primary components used for ESI contribution calculations.

Example

  • Basic Salary: ₹15,000

This amount would generally be considered for ESI wage calculations.


2. Dearness Allowance (DA)

Dearness Allowance (DA) is generally included in ESI wages.

DA is paid to employees to help address changes in the cost of living and forms part of the remuneration received under employment.

Example

  • Basic Salary: ₹15,000

  • DA: ₹3,000

The amount considered for ESI wage calculations would generally include both components, subject to the overall wage definition and applicable rules.


3. House Rent Allowance (HRA)

HRA is generally included in ESI wages when it is paid as part of the employee’s regular remuneration.

This is one area where HR professionals sometimes make incorrect assumptions because HRA is treated differently under different statutory frameworks.

For ESI purposes, the salary component should be examined based on the applicable definition of wages rather than automatically applying PF rules to ESI calculations.


4. Regular Allowances

Regular allowances paid as part of the employee’s remuneration may generally form part of ESI wages.

Examples may include:

  • Special allowance

  • City compensatory allowance

  • Other regular cash allowances

The exact treatment can depend on the nature and conditions of the payment.

A useful question for payroll teams is:

Is this amount paid regularly as part of the employee’s remuneration for employment?

If yes, it may need to be considered under the ESI wage definition.


5. Incentive Payments

Regular incentive payments may require careful examination.

If an incentive is paid as part of the employment arrangement, HR teams should review whether it falls within the definition of wages for ESI purposes.

Instead of automatically including or excluding incentives based only on their name, organizations should examine:

  • How frequently the payment is made

  • Whether it is part of the employment contract

  • Whether it is linked to regular work

  • The nature of the payment


What Is Generally Excluded From ESI Wages?

The ESI Act specifically excludes certain categories from the definition of wages.

1. Employer’s Contribution to PF or Pension Funds

Amounts paid by the employer as contributions to:

  • Provident Fund

  • Pension Fund

are generally excluded from ESI wages.

These contributions are employer benefits and are not treated as direct wages paid to the employee.


2. Travelling Allowance and Travel Expenses

Amounts paid to cover:

  • Travel expenses

  • Travelling allowances

  • Expenses incurred because of employment-related travel

are generally excluded when they represent genuine reimbursement or expenses related to employment.

However, HR teams should distinguish between actual expense reimbursement and a fixed allowance that may form part of regular remuneration.


3. Payments Made to Cover Special Employment Expenses

Payments made specifically to compensate an employee for expenses that arise because of the nature of employment may generally be excluded.

For example, a genuine reimbursement for expenses incurred while performing work duties may not be treated in the same way as a regular salary allowance.

Proper documentation is important.


4. Gratuity Payments

Gratuity payments are generally excluded from ESI wages.

Gratuity is a statutory or employment-related terminal benefit rather than regular monthly remuneration.


5. Payments Made During Certain Periods of Absence

The treatment of payments related to periods when an employee is not working requires careful consideration.

The ESI definition specifically addresses certain payments connected with periods of absence from work, including leave, lay-off, strike, or lockout, where the employee is not entitled to remuneration.

HR teams should review the exact circumstances and applicable rules before calculating contributions.


What About Overtime?

Overtime is a commonly misunderstood component.

Overtime wages are generally excluded from ESI contribution calculations.

However, overtime payments may still be relevant when considering other aspects of payroll or statutory compliance.

This is why employers should avoid applying one payroll rule to every compliance requirement.


What About Bonuses?

The treatment of bonuses depends on the type and nature of the payment.

Certain types of bonuses may be treated differently from regular wages.

For example, statutory or annual bonus payments may not always be handled in the same way as regular monthly remuneration.

HR teams should carefully review the nature of the bonus before deciding whether ESI contributions apply.


A Simple Example of ESI Wage Calculation

Consider the following salary structure:

Salary ComponentAmountGeneral ESI TreatmentBasic Salary₹15,000IncludedDearness Allowance₹2,000IncludedHRA₹5,000Generally includedSpecial Allowance₹3,000Depends on nature; often requires reviewOvertime₹1,500Generally excludedTravel Reimbursement₹1,000Generally excluded if genuine reimbursementTotal Gross Amount₹27,500Not automatically equal to ESI wages

The employer should determine the applicable ESI wage base by examining each component according to the statutory definition of wages.

This is why gross salary should not automatically be used as the ESI contribution base without reviewing the salary structure.


Common Mistakes HR Teams Make When Calculating ESI

1. Using Gross Salary Without Reviewing Components

A common mistake is calculating ESI on the entire gross salary without examining individual salary components.

Some items may be excluded, while others must be included.


2. Assuming PF Rules Apply to ESI

PF and ESI have different definitions and treatment of wage components.

A component excluded from PF calculations is not automatically excluded from ESI.


3. Incorrectly Excluding HRA

Some payroll teams automatically exclude HRA because of its treatment under other payroll or tax frameworks.

However, ESI calculations follow their own wage definition.


4. Treating Every Reimbursement as an Exclusion

A genuine reimbursement may be excluded, but organizations should maintain proper supporting documentation.

Simply naming a regular payment as a “reimbursement” does not automatically determine its treatment.


5. Ignoring Changes in Salary Structure

Promotions, salary revisions, and new allowances can change the composition of an employee’s remuneration.

HR teams should review ESI calculations whenever salary structures change.


The Importance of the ₹21,000 Wage Limit

For most employees, the ESI coverage wage limit is commonly ₹21,000 per month, subject to applicable provisions and exceptions.

Employees with wages within the prescribed limit may fall under ESI coverage if the establishment and employee meet the applicable eligibility requirements.

However, HR teams should remember that coverage and contribution obligations can be affected by factors such as:

  • The applicable contribution period

  • Wage changes during a contribution period

  • Existing employee coverage status

  • Applicable exemptions or special provisions

For this reason, employers should not automatically stop ESI contributions simply because an employee receives an increment that increases wages beyond the limit during an applicable contribution period.


A Simple ESI Compliance Checklist

Before finalizing monthly payroll, HR teams should check:

✔ Is the employee covered under the applicable ESI provisions?

✔ Have eligible wage components been correctly identified?

✔ Have excluded payments been properly documented?

✔ Are overtime payments handled correctly?

✔ Are reimbursements supported by relevant records?

✔ Have salary structure changes been reviewed?

✔ Are employee and employer contributions calculated correctly?

✔ Are contributions deposited within the required timeline?


How Payroll Software Can Help

Modern payroll software can simplify ESI compliance by helping organizations:

  • Maintain employee salary structures

  • Automatically calculate contributions

  • Track eligibility

  • Manage contribution records

  • Generate payroll reports

  • Reduce manual calculation errors

However, HR teams should periodically review software settings.

If a salary component is incorrectly configured, automation can repeat the same mistake every month.


Final Thoughts

Understanding ESI wage components is essential for accurate payroll and statutory compliance.

The most important point to remember is that ESI wages are not necessarily the same as an employee’s gross salary. Each payment component should be reviewed based on its nature and the applicable definition of wages.

Basic salary and DA generally form part of ESI wages, while certain items such as employer contributions to PF, genuine travel-related expenses, and gratuity are generally excluded. Other components, including allowances, incentives, and bonuses, may require a closer review depending on how they are structured and paid.

For HR and payroll teams, the safest approach is to maintain clear salary structures, document reimbursements properly, review changes regularly, and stay updated with official ESI requirements.

When there is uncertainty about a particular salary component, it is always better to verify the latest ESIC guidance or seek professional compliance advice before making a contribution decision.

Accurate ESI calculations not only help organizations avoid compliance issues—they also ensure that employees receive the social security protection they are entitled to.

14Sep

The First Year Matters: Why Early Employee Experiences Decide Whether Talent Stays

By , Afla KC , Digital Marketing Executive

Introduction

Hiring the right employee is only the beginning. The real challenge for businesses starts after the offer letter is signed.

An employee’s first year can strongly influence how they view the organisation, their role, their manager, and their future within the company. During this period, employees are not only learning their responsibilities—they are also deciding whether the organisation is the right place for them to build their career.

A positive first-year experience can create trust, engagement, confidence, and long-term commitment. A poor experience can lead to frustration, disengagement, and eventually resignation.

This is why organisations should look beyond recruitment and focus on what happens after a new employee joins.

From onboarding and manager support to workplace culture, communication, recognition, learning opportunities, and career development, every interaction contributes to an employee’s perception of the organisation.

For HR teams and business leaders, understanding the importance of the first year can help reduce unwanted turnover, strengthen employee engagement, and build a workplace where talented people want to stay.


Why the First Year Is So Important

The first year is a period of adjustment and discovery.

New employees are trying to understand:

  • What is expected from me?

  • How does this organisation work?

  • Can I trust my manager?

  • Will my work be recognised?

  • Is there an opportunity to grow?

  • Do I belong here?

  • Does the company’s culture match what was promised during recruitment?

These questions influence whether an employee develops a long-term connection with the organisation.

A strong first-year exp

erience answers these questions positively. A poor experience can create doubts that become increasingly difficult to overcome.


1. Onboarding Creates the First Real Impression

Recruitment creates expectations. Onboard

ing determines whether those expectations become reality.

A well-structured onboarding process helps employees understand:

  • Their role

  • Responsibilities

  • Team structure

  • Company policies

  • Tools and systems

  • Workplace culture

  • Performance expectations

Onboarding should not be limited to completing forms and collecting documents.

Employees should feel welcomed, supported, and prepared to contribute.

A thoughtful onboar

ding experience can make a new employee feel that the organisation genuinely values their decision to join.


2. The First Few Weeks Build Confidence

Starting a new job can be overwhelming.

Employees may be unfamiliar with:

  • Processes

  • Technology

  • Colleagues

  • Communication styles

  • Workflows

  • Internal expectations

HR and managers should provide clear guidance during this period.

Simple actions such as assigning a buddy, scheduling regular check-ins, and providing training can make a significant difference.

Employees who feel supported are more likely to become confident and productive.


3. Managers Have a Major Influence on Retention

An employee’s relationship with their manager can strongly influence their workplace experience.

A good manager:

  • Communicates clearly

  • Provides feedback

  • Sets realistic expectations

  • Recognises contributions

  • Supports development

  • Listens to concerns

  • Helps employees solve problems

Employees may enjoy their work but still consider leaving if they consistently experience poor management.

For this reason, organisations should invest not only in employees but also in developing effective managers.


4. Clear Expectations Reduce Workplace Frustration

Employees need to know what success looks like.

Unclear responsibilities can result in:

  • Confusion

  • Missed deadlines

  • Stress

  • Poor performance

  • Frustration

During the first year, managers should clearly communicate:

  • Job responsibilities

  • Performance goals

  • Key priorities

  • Evaluation criteria

  • Team expectations

Regular discussions can ensure employees understand whether they are progressing in the right direction.


5. Workplace Culture Becomes Visible After Joining

During recruitment, employees hear about company culture.

After joining, they experience it.

They notice:

  • How colleagues communicate

  • How managers behave

  • How mistakes are handled

  • Whether people are respected

  • How decisions are made

  • Whether employees feel heard

This gap between promised culture and experienced culture can influence retention.

If the workplace experience matches the organisation’s promises, trust grows.


6. Recognition Makes Employees Feel Valued

Employees want their contributions to matter.

Recognition doesn’t always need to involve financial rewards.

It can be as simple as:

  • Saying thank you

  • Recognising achievements publicly

  • Highlighting good work

  • Celebrating milestones

  • Giving constructive appreciation

Consistent recognition reinforces the idea that employees’ efforts are noticed.

A workplace where good work is regularly ignored can quickly become demotivating.


7. Learning Opportunities Encourage Employees to Stay

Talented employees often want opportunities to develop their skills.

During the first year, organisations can provide:

  • Training programmes

  • Mentorship

  • Workshops

  • Certifications

  • Cross-functional projects

  • Skill development plans

When employees can see how their current role contributes to their future career, they are more likely to view the organisation as a long-term opportunity.


8. Career Growth Should Not Be a One-Year Surprise

Employees should not have to wait for an annual appraisal to discuss their future.

Managers can start career conversations early.

Ask questions such as:

  • What skills would you like to develop?

  • Which areas interest you?

  • What responsibilities would you like to take on?

  • Where do you see yourself growing?

These conversations help employees understand that the organisation is interested in their long-term development.


9. Employee Feedback Should Start Early

HR teams should not wait until an employee resigns to ask what went wrong.

Regular feedback mechanisms can reveal problems before they become serious.

Organisations can use:

  • New-joiner surveys

  • One-on-one meetings

  • Pulse surveys

  • Stay interviews

  • Anonymous feedback

  • Manager check-ins

The important part is not simply collecting feedback—it is acting on it.


10. Workload and Well-Being Matter

A new employee may be enthusiastic during the first few months, but excessive workload can quickly lead to burnout.

Managers should monitor:

  • Workload

  • Working hours

  • Deadlines

  • Stress levels

  • Work-life balance

  • Team capacity

A sustainable work environment helps employees perform consistently without feeling overwhelmed.


11. Compensation Is Important, But It Isn’t Everything

Salary remains an important factor in employee retention.

However, employees evaluate their overall experience.

They may also consider:

  • Career growth

  • Management quality

  • Workplace culture

  • Recognition

  • Learning opportunities

  • Flexibility

  • Job security

  • Work-life balance

This means retention strategies should go beyond compensation alone.


12. Communication Builds Trust

Poor communication creates uncertainty.

Employees need timely information about:

  • Company changes

  • Team priorities

  • Performance

  • Policies

  • Expectations

  • Organisational decisions

Transparent communication helps employees understand what is happening around them.

Even when the news is difficult, honest communication can build more trust than silence.


A Practical First-Year Employee Journey

Organisations can structure the first year into different stages.

First Week

Focus on:

  • Welcome

  • Orientation

  • Documentation

  • Team introduction

  • Tools and access

First 30 Days

Focus on:

  • Role understanding

  • Training

  • Team integration

  • Initial goals

First 60–90 Days

Focus on:

  • Performance

  • Feedback

  • Skill development

  • Relationship building

Six Months

Focus on:

  • Career discussion

  • Performance review

  • Employee experience

  • Development opportunities

One Year

Focus on:

  • Overall performance

  • Career progression

  • Engagement

  • Future goals

  • Retention conversation

This structured approach ensures employees receive support throughout their first year rather than only during onboarding.


Warning Signs HR Teams Should Watch For

Some early warning signs may indicate that an employee is becoming disengaged.

These can include:

  • Reduced participation

  • Declining performance

  • Frequent complaints

  • Withdrawal from team activities

  • Lack of interest in development

  • Increased absenteeism

  • Reduced communication

None of these signs automatically mean an employee plans to leave, but they can indicate that a conversation is needed.

Managers should address concerns early instead of waiting for resignation.


How HR Teams Can Improve the First-Year Experience

A strong first-year employee experience requires coordination between HR, managers, and leadership.

Organisations can:

Create a Structured Onboarding Programme

Give every new employee a clear introduction to the company and their role.

Assign a Buddy or Mentor

A colleague can help new employees understand workplace processes and culture.

Schedule Regular Check-Ins

Don’t leave employees alone after their first week.

Set Clear Goals

Make expectations measurable and understandable.

Encourage Feedback

Give employees safe opportunities to share concerns.

Recognise Contributions

Celebrate progress throughout the year.

Create Development Plans

Connect employee skills with future opportunities.

Train Managers

Equip managers with communication, coaching, and feedback skills.


Why Retention Should Start Before Resignation

Many organisations begin thinking about retention only when an employee submits a resignation letter.

By that stage, it may already be too late.

Retention should begin from the moment a candidate accepts the offer.

The employee journey should be viewed as a continuous process:

Recruitment → Onboarding → Engagement → Development → Recognition → Career Growth → Retention

Every stage contributes to the employee’s decision to stay.


The Business Impact of a Strong First-Year Experience

Investing in employee experience can benefit organisations in several ways.

Lower Employee Turnover

Employees who feel supported and valued may be more likely to remain with the organisation.

Better Productivity

Clear expectations and effective onboarding help employees become productive faster.

Stronger Employer Brand

Employees who have positive experiences can become genuine advocates for the organisation.

Improved Team Culture

Engaged employees often contribute positively to workplace culture.

Reduced Recruitment Pressure

Better retention means businesses don’t have to continuously replace employees who leave.


Conclusion

The first year of employment is much more than an adjustment period. It is a critical stage during which employees form lasting opinions about their organisation, managers, colleagues, culture, and career opportunities.

A strong onboarding process can create a positive beginning, but retention requires much more. Employees need clear expectations, supportive managers, meaningful recognition, learning opportunities, career conversations, fair treatment, and consistent communication throughout their journey.

For HR teams, the goal should not simply be to help new employees settle in. It should be to create an environment where employees can see a future for themselves within the organisation.

Businesses that invest in the first-year employee experience are not only supporting their people—they are strengthening their organisation. When employees feel respected, supported, recognised, and connected to their future, staying becomes a natural choice rather than something the company has to constantly convince them to do.

The first year sets the tone. A great employee experience can turn a new hire into a long-term contributor, engaged team member, and future leader.

11Sep

Employee Resignation Documentation: What Should Be Recorded from Resignation to Relieving?

By Nandana G.S , Digital Marketing Executive

Employee resignation is not just the end of an employment relationship. From an HR perspective, it is a documentation and compliance process that should be handled carefully from the moment an employee submits resignation until the final relieving and settlement.

Proper resignation documentation helps businesses maintain accurate employee records, avoid misunderstandings, and provide evidence of decisions taken during the exit process.

1. Resignation Letter or Email

The process should begin with a clear record of the employee’s resignation.

HR should maintain:

  • Date of resignation

  • Employee’s name and designation

  • Resignation communication

  • Reason for resignation, if voluntarily provided

  • Proposed last working day

  • Notice period details

The original resignation email or letter should be preserved as part of the employee’s exit records.

2. Resignation Acknowledgement

HR should formally acknowledge the resignation and communicate the next steps to the employee.

The acknowledgement may include:

✔️ Acceptance of resignation ✔️ Notice period requirements ✔️ Proposed last working day ✔️ Handover expectations ✔️ Exit formalities ✔️ Company property return requirements

Clear communication at this stage can prevent confusion later.

3. Notice Period and Last Working Day

HR should maintain documentation showing how the notice period was calculated.

Any changes to the last working day should also be documented, particularly when there is:

  • Notice period waiver

  • Early release

  • Extension of notice period

  • Leave adjustment

  • Management-approved changes

Verbal agreements should not replace proper written documentation.

4. Handover Documentation

A structured handover process is essential, particularly for employees handling clients, projects, systems, finances, or critical business responsibilities.

The handover record may include:

  • Pending tasks

  • Project status

  • Client information

  • Important documents

  • System or process details

  • Responsible replacement/team member

  • Handover completion confirmation

This helps ensure business continuity after the employee leaves.

5. Exit Interview Records

An exit interview can provide valuable insights into employee experience and organizational issues.

HR may document feedback relating to:

  • Reason for leaving

  • Management experience

  • Work environment

  • Compensation and benefits

  • Career growth

  • Workload

  • Suggestions for improvement

Exit interview information should be handled appropriately and confidentially.

6. Company Assets and Access

Before relieving an employee, HR should coordinate with the relevant departments to confirm the return of company property.

This may include:

✔️ Laptop and other devices ✔️ ID cards and access cards ✔️ Documents and files ✔️ Keys ✔️ Other company assets

IT teams should also document the appropriate deactivation or modification of access to company systems, email, applications, and other business resources.

7. Leave and Attendance Records

The employee’s attendance and leave records should be reviewed before final settlement.

HR/payroll should verify:

  • Attendance up to the last working day

  • Leave balance

  • Leave encashment, where applicable

  • Unpaid leave

  • Notice-period attendance

  • Any approved adjustments

Accurate records help ensure the final payroll calculation is correct.

8. Full and Final Settlement Documentation

The Full and Final (FnF) settlement should be supported by proper calculations and records.

Depending on the employee’s circumstances, this may involve:

  • Salary payable

  • Leave encashment

  • Reimbursements

  • Incentives or variable pay, where applicable

  • Deductions

  • Advances or recoveries

  • Other applicable dues

HR and payroll teams should maintain supporting records for the settlement rather than relying only on the final payment entry.

9. Statutory and Employment Records

Employee exits may also require updates to applicable statutory and employment records.

Depending on the employee and applicable laws, HR should review relevant requirements relating to PF, ESI, TDS, gratuity, Professional Tax, and other statutory obligations.

The exact requirements can vary based on the employee’s circumstances and applicable law.

10. Relieving and Experience Documents

Once the exit process is completed, the organization should issue the appropriate employment documents according to its policies and applicable requirements.

Common documents may include:

  • Relieving letter

  • Experience/service certificate

  • Full and final settlement statement

  • Other applicable employment or statutory documents

The employee’s personnel file should also be updated to reflect the completed exit.

Common Resignation Documentation Mistakes

Many organizations create problems by:

❌ Accepting resignations without maintaining written records ❌ Failing to document changes to the last working day ❌ Relying on verbal handover confirmations ❌ Not reconciling leave and attendance ❌ Maintaining incomplete FnF calculations ❌ Delaying exit documentation ❌ Failing to update employee and statutory records ❌ Not maintaining a standardized exit checklist

A Simple Employee Exit Documentation Checklist

HR teams can use a structured checklist covering:

Resignation → Acknowledgement → Notice Period → Handover → Exit Interview → Asset Clearance → Attendance & Leave → FnF Settlement → Statutory Updates → Relieving & Experience Documents → Employee File Closure

Having a standardized process ensures that every employee exit is handled consistently.

How Level Up HR Solutions Can Help

At Level Up HR Solutions, we help businesses strengthen their HR processes through HR documentation, payroll compliance, statutory compliance, HR audits, employee record management, and HR policy support.

A properly documented employee exit protects both the organization and the employee by creating a clear record of what was communicated, completed, and settled.

Final Thoughts

Employee resignation should not be treated as simply receiving a resignation letter and issuing a relieving letter.

A well-managed exit process creates a complete, organized, and auditable trail from resignation to final settlement and relieving. For growing businesses, standardizing this process can significantly improve HR efficiency, documentation quality, and compliance readiness.

Level Up HR Solutions 📞 +91 8714805999 📧 info@leveluphrs.com 🌐 www.leveluphrs.com

#EmployeeResignation #EmployeeExitProcess #HRDocumentation #HRCompliance #PayrollCompliance #FullAndFinalSettlement #EmployeeRecords #HRIndia #StatutoryCompliance #HRManagement #KeralaBusiness #KochiBusiness #LevelUpHRSolutions

09Sep

Statutory Registers and Records: What HR Teams Need to Maintain

By , Afla KC , Digital Marketing Executive

Introduction

HR management is not limited to recruitment, employee engagement, attendance, and payroll. One of the most important responsibilities of an HR team is maintaining accurate statutory registers and employment records.

Statutory registers are official records that

businesses are required to maintain under applicable labour laws and regulations. These records help organisations demonstrate that they are complying with requirements related to wages, working hours, attendance, leave, employee benefits, employment conditions, and other statutory obligations.

For many businesses, maintaining these records can become challenging. Different labour laws may apply depending on factors such as th

e nature of the establishment, number of employees, location, industry, and applicable state rules. Poor record management can result in compliance gaps, difficulty during inspections, and unnecessary administrative work.

A structured statutory record-keeping system allows HR teams to stay organised, respond to audits more efficiently, and maintain transparency in employment practices.

In this guide, we will look at the

 key statutory registers and records HR teams may need to maintain, why they are important, common compliance mistakes, and how businesses can simplify statutory record management.


What Are Statutory Registers?

Statutory registers are records that an employer is required to maintain under applicable labour and employment laws.

They may contai

n information about:

  • Employees

  • Wages

  • Attendance

  • Working hours

  • Leave

  • Overtime

  • Deductions

  • Advances

  • Benefits

  • Employment details

  • Statutory contributions

These records provide documented evidence of how an organisation manages its workforce and fulfils its legal obligations.

The exact registers required can vary depending on the applicable central and state legislation.


Why Are Statutory Records Important?

Maintaining statutory records is important for several reasons.

1. Legal Compliance

Accurate records help demonstrate that the organisation is following applicable labour laws.

2. Audit and Inspection Readiness

Government auth

orities may require employers to produce specific records during inspections or audits.

3. Payroll Accuracy

Wage and attendance records support accurate salary calculations.

4. Employee Transparency

Proper documentation helps employees understand their wages, leave, deductions, and employment-related information.

5. Internal HR Management

Well-maintain

ed records make it easier for HR teams to manage employee information and resolve disputes.


1. Employee Master Records

An employee master record is one

of the most important HR records.

It generally contains relevant information such as:

  • Employee name

  • Employee identification details

  • Date of joining

  • Designation

  • Department

  • Employment category

  • Salary details

  • Contact information

  • Statutory identification details

  • Date of exit, where applicable

HR teams should ensure that employee information is updated whenever there is a change.


2. Attendance and Muster Records

Attendance records help organisations track employee presence and working patterns.

Depending on applicable requirements, records may include:

  • Date

  • Employee details

  • Attendance status

  • Working hours

  • Weekly offs

  • Holidays

  • Absence

  • Shift details

Attendance data can also support payroll calculations and overtime management.

Digital attendance systems can make this process easier while reducing manual errors.


3. Wage and Salary Registers

Wage records are particularly important for statutory compliance.

Depending on the applicable law, wage records may contain:

  • Employee details

  • Wage period

  • Basic wages

  • Allowances

  • Overtime

  • Gross wages

  • Deductions

  • Net wages

  • Payment details

Payroll records should be consistent with salary structures and applicable statutory requirements.


4. Overtime Records

If employees work beyond prescribed working hours and are eligible for overtime, appropriate records should be maintained.

These may include:

  • Employee name

  • Date of overtime

  • Number of overtime hours

  • Applicable overtime rate

  • Overtime amount

  • Payment details

HR teams should ensure that overtime is calculated according to the applicable legislation and establishment-specific rules.


5. Leave Records

Leave records help HR teams track employee leave entitlements and utilisation.

Depending on applicable rules, organisations may need to maintain information about:

  • Earned leave

  • Casual leave

  • Sick leave

  • Maternity leave

  • Other statutory leave

  • Leave balance

  • Leave taken

A digital leave management system can make tracking significantly easier.


6. Minimum Wage Records

Businesses must ensure that employees receive wages in accordance with applicable minimum wage requirements.

HR and payroll teams should maintain records that allow them to verify:

  • Applicable wage rates

  • Employee category

  • Basic wages

  • Allowances

  • Working days

  • Overtime

  • Total wages

Minimum wage requirements may differ based on the applicable state, scheduled employment, skill category, and other factors.


7. Statutory Deduction Records

Salary deductions should be properly recorded.

Depending on the employee and establishment, records may relate to:

  • Provident Fund

  • ESI

  • Professional Tax

  • TDS

  • Labour welfare-related deductions

  • Other legally permitted deductions

Each deduction should be accurately reflected in payroll records.


8. Provident Fund Records

For establishments covered under EPF requirements, HR and payroll teams need to maintain appropriate employee and contribution records.

These may include:

  • Employee PF details

  • UAN information

  • Employee contributions

  • Employer contributions

  • Wage details

  • Monthly contribution records

  • Challan/payment records

Accurate PF records are essential for both employee benefits and employer compliance.


9. ESI Records

For establishments and employees covered under ESI, relevant records may include:

  • Employee insurance details

  • ESI contribution information

  • Applicable wages

  • Employee contribution

  • Employer contribution

  • Payment records

HR teams should regularly review employee eligibility and update records when salary or employment details change.


10. Bonus Records

Where applicable, organisations should maintain records relating to statutory bonus calculations and payments.

Records may include:

  • Employee eligibility

  • Wage details

  • Bonus calculation

  • Amount paid

  • Payment date

Proper documentation helps HR teams demonstrate that applicable statutory bonus requirements have been addressed.


11. Maternity Benefit Records

Where applicable, employers should maintain appropriate records relating to maternity benefits.

These may include:

  • Employee details

  • Leave applications

  • Leave duration

  • Relevant supporting documents

  • Benefit payments

  • Return-to-work details

HR teams should handle maternity-related information carefully and maintain appropriate confidentiality.


12. Registers Related to Employee Deductions

Certain deductions from employee wages may be permitted only under applicable legal provisions.

HR teams should maintain appropriate records of:

  • Nature of deduction

  • Amount

  • Date

  • Reason

  • Supporting documentation

Unauthorised or incorrectly documented deductions can create compliance issues and employee disputes.


13. Employment and Appointment Records

Employee appointment documentation should be maintained systematically.

Important records may include:

  • Offer letters

  • Appointment letters

  • Employment agreements

  • Job descriptions

  • Salary revisions

  • Promotion letters

  • Transfer records

  • Resignation letters

  • Experience certificates

  • Full and final settlement records

These documents provide an important employment history for each employee.


14. Registers Related to Working Conditions

Depending on the establishment and applicable law, organisations may need records related to:

  • Working hours

  • Shifts

  • Weekly holidays

  • Rest intervals

  • Holidays

  • Overtime

  • Employee welfare facilities

These records help demonstrate that working conditions comply with applicable requirements.


15. Records Under Workplace Safety and Other Laws

Certain industries may have additional documentation requirements relating to:

  • Workplace safety

  • Accidents

  • Health and safety training

  • Protective equipment

  • Hazard management

  • Employee welfare

Factories, construction businesses, manufacturing units, and other higher-risk workplaces may have more extensive requirements than standard office environments.


Central Laws vs State-Specific Requirements

One of the biggest challenges for HR teams is understanding that statutory requirements are not always identical across India.

The records required may depend on:

  • State

  • Industry

  • Establishment type

  • Number of employees

  • Applicable labour legislation

  • Government notifications

For example, a company operating in multiple states may need to maintain different records or follow different procedural requirements depending on the applicable local rules.

Therefore, HR teams should avoid using a single generic compliance checklist for every business.


Digital vs Physical Statutory Records

Modern HR departments increasingly use digital systems to maintain statutory records.

Digital records can provide advantages such as:

  • Faster access

  • Better organisation

  • Automated calculations

  • Reduced paperwork

  • Easier reporting

  • Improved data accuracy

  • Secure backups

However, HR teams should confirm whether a particular record is permitted to be maintained electronically and whether specific formats, authentication, retention, or accessibility requirements apply.


How Long Should HR Records Be Maintained?

There is no single universal retention period for every HR record.

The required retention period can vary depending on:

  • Applicable legislation

  • Type of register

  • Nature of document

  • State-specific requirements

  • Tax requirements

  • Employment disputes

  • Company policies

HR teams should establish a documented record-retention policy based on the laws applicable to their organisation.

When in doubt, businesses should consult qualified labour-law or compliance professionals.


Common Statutory Compliance Mistakes

HR teams should watch out for common issues such as:

Incomplete Employee Records

Missing information can make compliance reporting difficult.

Inconsistent Payroll Data

Employee salary records, attendance, and statutory records should be aligned.

Delayed Updates

Salary changes, promotions, transfers, and exits should be updated promptly.

Missing Supporting Documents

Statutory claims should have appropriate documentation wherever required.

Using Outdated Formats

Organisations should ensure that their registers and processes reflect applicable current requirements.

Poor Record Security

Employee records contain confidential information and should be protected from unauthorised access.


How HR Teams Can Simplify Statutory Compliance

A structured approach can make statutory record management easier.

Step 1: Identify Applicable Laws

Determine which labour laws and statutory requirements apply to your organisation.

Step 2: Create a Compliance Checklist

List all required registers, records, filings, and deadlines.

Step 3: Assign Responsibility

Clearly identify who is responsible for maintaining each record.

Step 4: Digitise Where Appropriate

Use HRMS and payroll software to automate routine data collection.

Step 5: Conduct Regular Audits

Review records periodically to identify missing or inconsistent information.

Step 6: Maintain Backups

Ensure important records are securely backed up.

Step 7: Monitor Regulatory Changes

Labour laws and compliance requirements can change, so HR teams should regularly review updates.


The Role of HRMS in Statutory Record Management

An HRMS can bring employee information, attendance, payroll, leave, and statutory records into one system.

It can help businesses:

  • Maintain employee databases

  • Track attendance

  • Manage leave

  • Process payroll

  • Calculate statutory contributions

  • Generate reports

  • Store documents

  • Track compliance activities

Automation reduces repetitive administrative work and gives HR teams better visibility into compliance.

However, software configuration should be reviewed whenever applicable statutory requirements change.


Statutory Records Checklist for HR Teams

A practical HR checklist may include:

✓ Employee master records

✓ Attendance and muster records

✓ Wage and salary records

✓ Overtime records

✓ Leave records

✓ Minimum wage-related records

✓ PF records

✓ ESI records

✓ Professional Tax records, where applicable

✓ TDS and payroll tax records

✓ Bonus records, where applicable

✓ Maternity benefit records, where applicable

✓ Appointment and employment records

✓ Working-hours records

✓ Accident and safety records, where applicable

✓ Statutory payment records

✓ Required returns and filings

The exact list should always be customised based on the organisation’s location, industry, workforce, and applicable legislation.


Conclusion

Statutory registers and records are an essential part of effective HR management. They provide organisations with documented evidence of compliance while supporting accurate payroll, employee administration, audits, inspections, and workplace management.

For HR teams, the key challenge is not simply maintaining a large number of documents. It is identifying which requirements apply to the organisation and ensuring that records remain accurate, complete, updated, secure, and accessible.

Businesses should regularly review their statutory compliance requirements, maintain a centralised checklist, establish clear responsibilities, and use appropriate HR and payroll technology to reduce manual work.

A proactive approach to statutory record management can help organisations identify compliance gaps before they become serious problems. More importantly, it creates a structured HR environment where employee information, payroll records, statutory contributions, and employment documentation can be managed efficiently.

In a changing regulatory environment, HR teams should treat statutory compliance as an ongoing process rather than a once-a-year activity. Regular audits, updated policies, reliable documentation, and professional compliance support can help businesses maintain stronger and more organised HR operations.

Important note: The exact statutory registers, formats, retention periods, and filing requirements applicable to an organisation depend on the relevant central and state laws, establishment type, industry, workforce size, and applicable notifications. HR teams should verify current requirements before relying on a generic checklist.

08Sep

POSH Policy: What Every Employer Should Include and Maintain

By Nandana G.S , Digital Marketing Executive

A strong POSH (Prevention of Sexual Harassment) Policy is more than a document kept in the HR folder. It is an important workplace framework that helps organizations prevent sexual harassment, establish a clear complaint mechanism, and ensure that employees understand their rights and responsibilities.

Under India’s Sexual Harassment of Women at Workplace (Prevention, Prohibition and Redressal) Act, 2013, employers have specific responsibilities regarding prevention, awareness, complaint handling, and workplace compliance.

What Should a POSH Policy Include?

A well-drafted POSH Policy should clearly address the following:

1. Purpose and Scope

The policy should explain why it exists and who it applies to. It should cover employees and, where relevant, interns, trainees, consultants, contract workers, visitors, and other individuals interacting with the workplace.

2. Clear Definition of Sexual Harassment

The policy should explain what constitutes sexual harassment and provide examples of prohibited conduct.

These may include:

  • Unwelcome physical contact or advances

  • Requests or demands for sexual favours

  • Sexually coloured remarks

  • Showing or sharing sexually explicit material

  • Other unwelcome physical, verbal, or non-verbal conduct of a sexual nature

3. Internal Committee Details

Where applicable, the organization should constitute an Internal Committee (IC) as required by law.

The policy should clearly communicate:

✔️ Committee composition ✔️ Roles and responsibilities ✔️ Contact details of committee members ✔️ Complaint-handling responsibilities ✔️ Procedures for dealing with complaints

4. Complaint Procedure

Employees should know how and where to submit a complaint.

The policy should explain the complaint process, applicable timelines, confidentiality expectations, and the general stages involved in inquiry and resolution.

5. Confidentiality

POSH matters involve sensitive information. The policy should emphasize appropriate confidentiality throughout the complaint and inquiry process and restrict disclosure to those who are legally or legitimately required to know.

6. Protection Against Retaliation

Employees should be able to raise genuine concerns without fear of retaliation or victimization. The policy should clearly state the organization’s commitment to maintaining a safe reporting environment.

7. Awareness and Training

A policy is effective only when employees know it exists.

Employers should conduct appropriate POSH awareness programs and training, particularly for employees and Internal Committee members.

8. Records and Documentation

HR teams should maintain relevant documentation, including:

  • POSH policy and updates

  • Internal Committee constitution records

  • Training and awareness records

  • Complaint and inquiry documentation

  • Annual reporting records, where applicable

  • Other statutory records and communications

POSH Compliance Is an Ongoing Responsibility

Simply creating a POSH policy does not mean an organization is fully compliant.

Businesses should regularly review whether their policy is current, whether the Internal Committee is properly constituted, whether employees have received awareness training, and whether required records and reporting processes are being maintained.

For growing organizations, POSH compliance should be treated as part of the overall HR compliance framework—not as a one-time documentation exercise.

Common POSH Compliance Gaps

Organizations may face challenges when they:

❌ Have an outdated POSH policy ❌ Fail to communicate the policy to employees ❌ Do not properly maintain Internal Committee records ❌ Skip mandatory awareness initiatives ❌ Lack a clearly communicated complaint mechanism ❌ Maintain incomplete documentation ❌ Treat POSH compliance as only an HR formality

How Level Up HR Solutions Can Help

At Level Up HR Solutions, we help businesses strengthen their HR compliance framework through HR policy documentation, statutory compliance support, HR audits, payroll compliance, and proper employee documentation.

A well-maintained POSH framework can help organizations build a workplace where employees feel safe, respected, informed, and protected.

Final Thoughts

POSH compliance is not simply about having a policy on paper. It is about creating a workplace system that prevents harassment, enables responsible reporting, protects confidentiality, and supports fair resolution.

For employers, regular review, employee awareness, proper documentation, and effective implementation are key to maintaining a compliant and responsible workplace.

Note: POSH requirements can depend on the organization’s circumstances and current legal requirements. Employers should verify the latest statutory provisions and applicable rules when drafting or updating their policy.

Level Up HR Solutions 📞 +91 8714805999 📧 info@leveluphrs.com 🌐 www.leveluphrs.com

#POSH #POSHCompliance #HRCompliance #WorkplaceSafety #SexualHarassmentPrevention #HRIndia #EmployeeRights #HRPolicy #StatutoryCompliance #WorkplaceCulture #KeralaBusiness #KochiBusiness #LevelUpHRSolutions

07Sep

How to Prepare Your HR Department Before an Internal Compliance Review

by Naziha , Digital Marketing Executive

An internal compliance review can be stressful for any HR department. Suddenly, teams may start searching for missing employee files, checking payroll records, reviewing company policies, and trying to understand whether important statutory requirements have been followed correctly.

However, an internal compliance review should not be viewed as something to fear.

When handled properly, it is an opportunity to identify gaps, correct mistakes, strengthen HR processes, and reduce the risk of serious problems in the future.

In 2026, HR compliance has become more important than ever. Organizations must manage employee documentation, payroll obligations, statutory contributions, workplace policies, employee benefits, data privacy, and other legal responsibilities. Even small mistakes can create operational difficulties and expose a business to financial or legal risks.

The good news is that proper preparation can make an internal compliance review much easier.

This guide explains how HR departments can prepare effectively before an internal compliance review and build a stronger, more organized compliance system.

What Is an Internal HR Compliance Review?

An internal HR compliance review is a systematic assessment of an organization’s HR practices, policies, records, and procedures.

The purpose is to identify whether the organization is following applicable laws, statutory requirements, and internal company policies.

An internal review may examine areas such as:

  • Employee documentation

  • Employment contracts

  • Payroll records

  • Attendance and leave management

  • Statutory compliance

  • Workplace policies

  • Employee benefits

  • Training records

  • Disciplinary procedures

  • Employee exit processes

Unlike an external inspection, an internal review gives organizations an opportunity to identify and correct problems proactively.

Why Preparing for an Internal Compliance Review Matters

Many compliance problems develop slowly.

For example, a missing employee document may initially seem like a minor administrative issue. However, when combined with incomplete payroll records, outdated policies, or inaccurate statutory calculations, it can become a much larger compliance concern.

Preparing in advance helps organizations:

  • Identify missing documents

  • Correct inaccurate employee records

  • Improve payroll accuracy

  • Update outdated policies

  • Strengthen internal procedures

  • Reduce legal and financial risks

  • Prepare for future audits or inspections

A well-prepared HR department can also complete the review process faster and with greater confidence.

1. Create a Clear Compliance Review Checklist

The first step is to understand exactly what needs to be reviewed.

HR teams should create a structured checklist covering all major compliance areas.

A basic checklist may include:

Employee Records
  • Employment contracts

  • Offer letters

  • Appointment letters

  • Identity documents

  • Address verification records

  • Educational and experience certificates

Payroll Records
  • Salary structures

  • Payslips

  • Attendance records

  • Overtime records

  • Salary revision letters

  • Tax-related documentation

Statutory Compliance
  • PF records

  • ESI records

  • TDS documentation

  • Labour Welfare Fund requirements, where applicable

  • Other applicable statutory records

HR Policies
  • Leave policy

  • Attendance policy

  • Code of conduct

  • Workplace safety policies

  • Grievance procedures

  • Data protection policies

A checklist ensures that important areas are not overlooked during preparation.

2. Review Employee Documentation

Employee files are one of the first areas that should be reviewed before an internal compliance assessment.

HR teams should check whether employee records are:

  • Complete

  • Accurate

  • Updated

  • Properly organized

  • Securely stored

Important documents may include:

  • Signed employment agreements

  • Offer and appointment letters

  • Employee identification documents

  • Salary information

  • Bank account details

  • Policy acknowledgements

  • Performance records

If any information is missing, HR teams should identify the gap and take appropriate action before the review.

3. Verify Payroll Accuracy

Payroll errors can create serious compliance and employee relations problems.

Before an internal review, organizations should verify:

  • Salary calculations

  • Attendance information

  • Leave deductions

  • Overtime payments

  • Incentives and bonuses

  • Employee deductions

Payroll teams should also ensure that supporting documents are available for major salary changes.

For example, if an employee received a salary revision, there should be appropriate documentation supporting that change.

Regular payroll reviews can significantly reduce the risk of unexpected discrepancies.

4. Check PF, ESI, TDS and Other Statutory Records

Statutory compliance should be a major focus during any HR compliance review.

Organizations should carefully review whether applicable contributions, deductions, and records have been managed correctly.

Depending on the organization and location, this may include:

  • Employees’ Provident Fund (PF)

  • Employees’ State Insurance (ESI)

  • Tax Deducted at Source (TDS)

  • Professional Tax

  • Labour Welfare Fund (LWF)

HR and payroll teams should check whether:

✔ Eligible employees have been properly registered.

✔ Contributions and deductions have been calculated correctly.

✔ Payments have been completed within applicable deadlines.

✔ Records and supporting documentation are available.

✔ Employee information has been updated where necessary.

Any uncertainty should be reviewed with a qualified payroll or compliance professional.

5. Review Attendance and Leave Management

Attendance and leave records directly affect payroll and employee management.

Common problems include:

  • Missing attendance records

  • Incorrect leave balances

  • Unapproved absences

  • Inconsistent leave approvals

  • Manual tracking errors

Before the compliance review, HR teams should ensure that attendance information is accurate and properly documented.

Important records include:

  • Attendance reports

  • Leave applications

  • Leave approvals

  • Work-from-home approvals, where applicable

  • Shift schedules

  • Overtime records

A structured attendance system makes the review process significantly easier.

6. Update Company Policies

Outdated policies can create unnecessary risks.

Businesses should regularly review whether their policies still reflect:

  • Current workplace practices

  • Applicable regulations

  • Organizational requirements

  • Changes in work arrangements

Important policies may include:

  • Leave and attendance policies

  • Code of conduct

  • Disciplinary procedures

  • Workplace harassment policies

  • Grievance procedures

  • Data privacy policies

  • Remote work policies

Employees should also be informed whenever significant policies are updated.

Where appropriate, organizations should maintain records showing that employees have received or acknowledged important policies.

7. Review Employee Grievances and Disciplinary Records

Employee relations issues require careful documentation.

HR teams should review whether records are available for:

  • Employee complaints

  • Grievances

  • Workplace investigations

  • Warning letters

  • Disciplinary actions

  • Corrective measures

The purpose is not simply to collect documents. Organizations should ensure that procedures have been applied consistently and appropriately.

Incomplete or inconsistent documentation can make workplace disputes more difficult to manage.

8. Check Training and Policy Awareness Records

A policy is only effective when employees understand it.

During an internal compliance review, HR teams should check whether employees have received appropriate training and communication regarding important workplace requirements.

This may include:

  • Compliance training

  • Workplace safety training

  • Data security awareness

  • Code of conduct training

  • Anti-harassment awareness

  • HR policy communication

Maintain records of:

  • Training dates

  • Participants

  • Training materials

  • Employee acknowledgements

These records demonstrate that the organization has actively communicated important requirements.

9. Review Employee Exit Procedures

Employee exits should also be included in the compliance review.

Organizations should verify that former employee records include, where applicable:

  • Resignation letters

  • Acceptance of resignation

  • Notice period records

  • Full and final settlement documentation

  • Asset return records

  • Access revocation confirmation

  • Experience or relieving letters

A poor exit process can create both compliance and security risks.

For example, failure to revoke access to company systems after an employee leaves can expose confidential business information.

10. Organize Documents in One Central System

One of the biggest challenges during compliance reviews is finding documents quickly.

When records are scattered across:

  • Email inboxes

  • Personal computers

  • Messaging applications

  • Multiple spreadsheets

  • Physical files

the review process becomes slow and inefficient.

A centralized HR documentation system can help organizations:

  • Access records quickly

  • Improve document security

  • Reduce duplication

  • Track missing documents

  • Simplify audits

  • Improve overall efficiency

Digital HR and payroll systems can also help automate routine compliance activities.

11. Conduct a Mock Internal Audit

One of the most effective ways to prepare is to conduct a small mock review before the actual internal compliance assessment.

Assign an HR team member to review records as if they were an auditor.

Ask questions such as:

  • Can we locate employee records quickly?

  • Are important documents signed?

  • Are payroll records accurate?

  • Are statutory records complete?

  • Are policies up to date?

  • Are there any missing employee acknowledgements?

A mock audit helps identify gaps before the official review begins.

12. Prepare an Action Plan for Identified Gaps

Finding problems during an internal review is not necessarily a failure.

In fact, identifying issues early is one of the main purposes of conducting the review.

For every identified gap, create a clear action plan.

The plan should include:

  • The identified issue

  • The corrective action required

  • The responsible person or department

  • The expected completion date

For example:

Compliance GapRequired ActionMissing employee documentsCollect and securely update recordsOutdated leave policyReview and revise the policyPayroll discrepancyVerify calculations and correct errorsMissing training recordsUpdate the training documentation process

This approach helps organizations move from simply identifying problems to actively resolving them.

Common Mistakes to Avoid Before a Compliance Review

Waiting Until the Last Minute

Compliance preparation should be continuous rather than rushed immediately before an audit.

Ignoring Small Documentation Gaps

Small problems can become significant issues when they affect multiple employees or processes.

Assuming Old Policies Are Still Relevant

Policies should be reviewed periodically to ensure they remain appropriate.

Focusing Only on Payroll

Compliance covers much more than salary processing. Documentation, policies, employee relations, and data protection are equally important.

Not Following Up on Identified Problems

Finding a compliance gap is only useful if corrective action is taken.

How Technology Can Simplify Compliance Preparation

Modern HR technology can significantly improve compliance management.

HR and payroll systems can help organizations:

  • Maintain centralized employee records

  • Automate payroll calculations

  • Track attendance and leave

  • Store policy acknowledgements

  • Monitor compliance deadlines

  • Generate reports

  • Reduce manual errors

However, technology should support strong processes rather than replace them completely.

Regular human review remains important.

Final Thoughts

Preparing for an internal HR compliance review should not be treated as a last-minute exercise.

The strongest HR departments maintain compliance throughout the year by keeping employee records updated, reviewing payroll regularly, monitoring statutory requirements, and maintaining clear workplace policies.

An internal review provides an opportunity to answer an important question:

Are our HR processes actually working as intended?

If the answer reveals gaps, organizations should view them as opportunities for improvement.

By preparing systematically, maintaining accurate documentation, conducting regular internal checks, and taking corrective action quickly, HR departments can reduce compliance risks and build stronger, more reliable systems.

In 2026, compliance is not just about being prepared for an audit. It is about creating an organized, transparent, and accountable workplace every day.

04Sep

Copy of How Employee Investment Declarations Affect TDS Calculation

By Afla KC , Digital Marketing Executive

Introduction

Tax Deducted at Source (TDS) is an important part of salary processing in India. For employers, calculating the correct amount of TDS requires more than simply applying a tax rate to an employee’s monthly salary. Payroll teams need to consider salary structure, applicable tax regime, eligible deductions, exemptions, and the information employees provide during the financial year.

One of the most important inputs in this process is the employee investment declaration.

Employees are often asked by their employers to declare their proposed investments and eligible tax-saving expenses at the beginning of, or during, a financial year. This information helps the payroll team estimate the employee’s taxable income and calculate the appropriate amount of TDS from salary.

However, investment declarations can also create confusion. Employees may declare investments they intend to make but fail to actually make them. Others may submit declarations late or provide incomplete information. If the final proof submitted later differs from the original declaration, the employer may need to recalculate the employee’s taxable income and adjust TDS accordingly.

Understanding how investment declarations affect TDS is therefore essential for both employees and HR teams.

This guide explains what investment declarations are, how they influence salary TDS, what documents employees may need to submit, and how HR and payroll teams can manage the process efficiently.


What Is an Employee Investment Declaration?

An investment declaration is information provided by an employee to their employer regarding investments, expenses, and other eligible items that may qualify for tax benefits under the applicable income-tax provisions.

The declaration generally helps the employer estimate the employee’s taxable salary for TDS purposes.

Depending on the employee’s applicable tax regime and eligibility, declarations may relate to items such as:

  • Life insurance prem

  • iums

  • Provident Fund contributions

  • Public Provident Fund (PPF)

  • Eligible tuition fees

  • Certain housing loan-related amounts

  • Health insurance premiums

  • Eligible donations

  • Other permitted deductions or exemptions

The exact tax treatment depends on the applicable provisions and the tax regime selected by the employee.


Why Do Employers Collect Investment Declarations?

Employers are responsible for deducting TDS from salary based on the employee’s estimated taxable income.

To ma

ke this calculation accurately, payroll teams need relevant information from employees.

Investment declarations help employers:

  • Estimate annual taxable income

  • Calculate eligible deductions

  • Spread estimated TDS across monthly payroll

  • Reduce the possibility of large year-end adjustments

  • Main

  • tain appropriate payroll records

For employees, submitting accurate information can help ensure that TDS is deducted more appropriately throughout the financial year rather than creating an unexpected tax adjustment later.


How Investment Declarations Affect TDS

The basic process can be understood through a simple calculation.

Step 1: Calculate Estimated Annual Salary

The employer estimates the employee’s annual taxable salary based on salary components and expected earnings.

Step 2: Consider Applicable Exemptions and Deductions

Eligible exemptions and deductions are considered based on the employee’s tax regime and applicable rules.

Step 3: Estimate Taxable Income

The estimated taxable income is calculated after considering eligible deductions and other applicable adjustments.

Step 4: Calculate Estimated Annual Tax

The employer calculates the estimated tax liability based on the applicable tax rates and provisions.

Step 5: Deduct TDS Through Payroll

The estimated annual tax is generally spread across the remaining salary payments during the financial year.

Therefore, the investment declaration can directly influence the amount of TDS deducted from an employee’s monthly salary.


The Importance of Choosing the Correct Tax Regime

One of the first things employees need to understand is the tax regime applicable to them.

India currently has two personal income-tax regimes:

  • The new tax regime

  • The old tax regime

The availability and treatment of deductions and exemptions can differ significantly between the two.

Employees should therefore understand which tax regime they are using before making investment declarations to their employer.

A declaration that may provide a tax benefit under the old regime may not provide the same benefit under the new regime.

This makes tax-regime selection an important part of the payroll TDS process.


Common Investments Employees Declare

Depending on eligibility and the applicable tax regime, employees may declare several types of investments or expenses.

Section 80C Investments

Under the applicable provisions, eligible investments and payments may include:

  • Employee’s contribution to certain provident fund schemes

  • Public Provident Fund

  • Life insurance premiums

  • Eligible tuition fees

  • Certain housing loan principal repayments

  • Other qualifying investments

The overall deduction is subject to the limits and conditions prescribed under the Income-tax Act.


Health Insurance Premiums

Eligible health insurance premiums may qualify for deduction under the applicable provisions, subject to prescribed conditions and limits.

Employees should retain appropriate premium receipts or other supporting documents when required.


Home Loan-Related Claims

Employees with eligible housing loans may be able to claim certain tax benefits relating to:

  • Principal repayment

  • Interest on housing loans

The actual tax treatment depends on factors such as the nature of the property, loan conditions, applicable provisions, and tax regime.

Payroll teams should therefore avoid treating every home-loan claim as automatically deductible.


Rent and Other Exemptions

Depending on the employee’s salary structure and tax regime, certain rent-related or other eligible exemptions may be relevant.

For example, eligible employees receiving House Rent Allowance (HRA) may be able to claim exemption under the applicable provisions if the required conditions are satisfied.

The payroll team should calculate such exemptions according to the prescribed rules rather than simply accepting the employee’s declared amount.


Declaration vs Investment Proof

One of the most important distinctions in payroll processing is the difference between a declaration and proof.

Investment Declaration

This generally represents what an employee expects or intends to invest or spend during the financial year.

Investment Proof

This provides supporting evidence that the investment or eligible expense was actually made or incurred.

For example, an employee may declare that they intend to make an eligible investment of ₹1,00,000 during the year.

If they ultimately invest only ₹70,000, the employer may need to revise the tax calculation based on the actual eligible amount when proof is collected.

Therefore:

Declaration = Estimated claim

Proof = Supporting evidence of the actual claim

This distinction is critical for accurate year-end TDS processing.


What Happens When the Declared Investment Is Not Made?

Suppose an employee declares eligible investments of ₹1,50,000 but ultimately makes only ₹1,00,000 of eligible investments.

The employer cannot continue treating the full ₹1,50,000 as an eligible tax benefit if the applicable requirements are not satisfied.

The payroll team may need to:

  1. Recalculate taxable income.

  2. Remove the unsupported benefit.

  3. Recalculate estimated tax liability.

  4. Adjust TDS in the remaining months.

This can result in higher TDS deductions toward the end of the financial year.

Employees should therefore avoid declaring investments simply to reduce monthly TDS unless they genuinely expect to make the eligible investments.


What Happens If an Employee Submits Proof Late?

If investment proof is not submitted within the employer’s specified deadline, the payroll team may be unable to consider the claim while processing salary TDS for that period.

This can increase the TDS deducted from salary.

However, employees may still be able to claim eligible deductions while filing their income-tax return, subject to the applicable law and their tax regime.

Therefore, employees should follow their employer’s declaration and proof-submission timelines carefully.


Example of How Declarations Affect TDS

Consider an employee with an estimated annual taxable income of ₹10,00,000 before considering certain eligible deductions.

Suppose the employee declares ₹1,00,000 of eligible investments under provisions applicable to their selected tax regime.

The employer may consider the eligible amount while estimating taxable income.

If the claim is accepted under the applicable rules:

Estimated income: ₹10,00,000

Less eligible deduction: ₹1,00,000

Estimated taxable income: ₹9,00,000

The estimated tax liability would then be calculated based on the applicable tax regime and rates.

However, if the employee later provides proof for only ₹60,000, the payroll team may need to revise the calculation.

This could increase taxable income by ₹40,000 and consequently increase the remaining TDS deductions.

This example is simplified; actual TDS depends on the employee’s complete salary structure, tax regime, deductions, exemptions, and applicable provisions.


Role of HR and Payroll Teams

HR and payroll departments play an important role in managing investment declarations.

A structured process should include:

1. Communicating Deadlines

Employees should clearly know when declarations and proofs need to be submitted.

2. Providing Guidelines

Payroll teams should explain which documents are generally required and which claims may be considered.

3. Verifying Supporting Documents

Proofs should be reviewed according to the employer’s payroll process and applicable requirements.

4. Updating Payroll

Approved changes should be reflected in the employee’s taxable income and TDS calculation.

5. Maintaining Records

Appropriate records should be maintained for payroll and statutory purposes.


Common Mistakes Employees Should Avoid

Employees frequently make mistakes during investment declaration.

Some common examples include:

  • Declaring investments they do not intend to make

  • Submitting incorrect amounts

  • Choosing the wrong tax regime

  • Missing submission deadlines

  • Providing incomplete documents

  • Assuming every investment qualifies for a deduction

  • Confusing tax declarations with actual investments

  • Waiting until the final month to review tax planning

Accurate and timely information makes payroll processing much smoother.


Common Mistakes HR Teams Should Avoid

Payroll teams should also watch for:

  • Applying deductions without considering eligibility

  • Failing to update salary changes

  • Not communicating deadlines clearly

  • Incorrectly carrying forward declared amounts

  • Ignoring differences between declarations and proofs

  • Not maintaining proper documentation

  • Using outdated tax rules or thresholds

Regular payroll reviews can reduce these risks.


How Payroll Software Can Improve TDS Management

Manual TDS calculations can become challenging when organisations have a large workforce.

Payroll software can help HR teams:

  • Collect employee declarations

  • Store supporting documents

  • Track submission deadlines

  • Calculate estimated taxable income

  • Update TDS calculations

  • Maintain employee tax records

  • Generate payroll reports

Automation reduces repetitive work and helps payroll teams maintain consistency.

However, software calculations should always be configured and reviewed according to the applicable tax rules.


Best Practices for Employees

Employees can make the process easier by:

  • Understanding their selected tax regime

  • Declaring only realistic investments

  • Keeping investment documents safely

  • Submitting declarations on time

  • Providing accurate proof

  • Reviewing monthly payslips

  • Checking TDS deductions periodically

  • Planning investments throughout the year

Good tax planning is not about making last-minute investments simply to reduce TDS. It is about making financially appropriate decisions while understanding the available tax provisions.


Best Practices for HR and Payroll Teams

Businesses can improve their investment declaration process by creating a structured workflow:

Step 1: Communicate the tax declaration process.

Step 2: Provide clear submission deadlines.

Step 3: Collect employee declarations digitally where possible.

Step 4: Review supporting documents.

Step 5: Update payroll calculations.

Step 6: Reconcile declared amounts with actual proofs.

Step 7: Recalculate TDS where required.

Step 8: Maintain accurate records.

This approach reduces confusion for both employees and payroll teams.


Conclusion

Employee investment declarations play an important role in salary TDS calculation. They provide employers with information needed to estimate an employee’s taxable income and calculate TDS during the financial year. However, a declaration is not the same as proof, and the final tax calculation must reflect the employee’s actual eligibility under the applicable tax rules.

For employees, the best approach is to declare investments accurately, understand the tax regime they are using, submit required documents on time, and avoid making unrealistic claims. For HR and payroll teams, a clear process for collecting, verifying, and updating investment information can significantly reduce errors and last-minute TDS adjustments.

As payroll processes become increasingly digital, organisations can use payroll software and structured workflows to simplify investment declarations, document management, and TDS calculations. When employees and employers work together with accurate information and timely documentation, salary tax processing becomes more transparent, efficient, and predictable.

Ultimately, effective investment declaration management benefits everyone. Employees get greater clarity about their tax deductions, while organisations can maintain a more accurate and compliant payroll process.